downloadGroupGroupnoun_press release_995423_000000 copyGroupnoun_Feed_96767_000000Group 19noun_pictures_1817522_000000Member company iconResource item iconStore item iconGroup 19Group 19noun_Photo_2085192_000000 Copynoun_presentation_2096081_000000Group 19Group Copy 7noun_webinar_692730_000000Path
Skip to main content
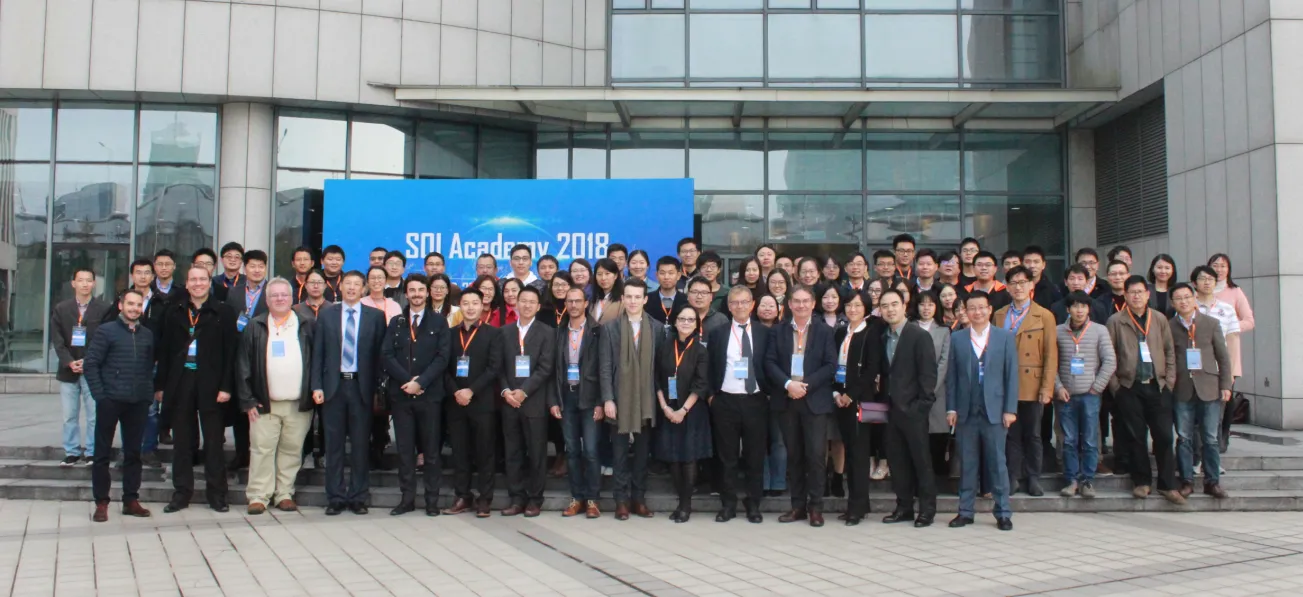
There were over 220 participants at the recent SOI Academy FD-SOI Training event organized in Shanghai. The event extended over two days, with the first day covering a basic introduction to the technology as well as the ecosystem worldwide and in China. The second day was hands-on professional training. Attendees got a comprehensive understanding of how to leverage the benefits and flexibility of FD-SOI design techniques for low-power chips including logic, mixed-signal/RF and analog blocks. They had a great line-up of experts from whom to learn – check out the agenda here. There was also a follow-up press release (in Chinese) from SITRI here. There will be more of these SOI Academy events in cities across China in the year to come – we'll keep you posted (and of course, keep checking back for news on the Consortium's Events page). [caption id="attachment_12981" align="aligncenter" width="1000"] SOI Academy '18 keynotes by: Dr. Mark Ding, CEO, SITRI; Dr. Carlos Mazure, EVP Soitec and Chairman/Executive Director SOI Consortium. Dr. Julien Arcamone, EVP Leti. (Images courtesy: SITRI). Lower right: the hands-on FD-SOI training.[/caption] The two-day seminar and hands-on FD-SOI design training was (superbly!) co-organized by SITRI and Leti, with the support of the SOI Industry Consortium at the Jiading SIMIT campus outside of Shanghai. Just to put this in perspective, SIMIT and SITRI are absolutely key players in China's chip ecosystem. SIMIT is the Shanghai Institute of Microsystem and Information Technology, one of the most venerable institutes in the Chinese Academy of Science (CAS) and one of the world's earliest pioneers in SOI. SITRI is the Shanghai Industrial μTechnology Research Institute, an international innovation center focused on globally accelerating innovation and commercialization of More-than-Moore for IoT. Both institutions are under the aegis of Dr. Xi Wang, Chairman of SITRI, Director General of SIMIT, Academician of CAS, and champion of all things SOI in China. At this Shanghai event, the participants came from industry (including big companies, SMEs and startups) and technical institutions. In fact as well as attendees from Shanghai people voyaged from other cities such as Shenzhen and Chengdu. The designers participating to the FD-SOI training day were all experienced in design and highly motivated in learning FD-SOI design, notes Carlos Mazure, Chairman Executive Director of the SOI Industry Consortium, and Executive VP of Soitec. “This made it possible to dive into the specificities of FD-SOI,” he said, adding that, “The focus on RF was very timely.” Day 1: Intro to FD-SOI The first afternoon opening keynotes were made by SITRI CEO Dr. Mark Ding and Leti EVP Dr. Julien Arcamone. These were followed by overview talks by execs from Soitec, Verisilicon and GlobalFoundries. After a lively networking break, three talks delved into FD-SOI technology. The first was by Professor Sorin Cristoloveanu, Laureate of the IEEE Andrew Grove Award and Director at the CNRS (the French National Center for Scientific Research – the largest governmental research organization in France and the largest fundamental science agency in Europe). He covered device physics and characterization techniques. This was followed by talks on the technology by Soitec Fellow Bich-Yen Nguygen, and by Dr. Christophe Tretz, IBM Sr. Engineer on product design methodology. The day ended with a dinner, where Professor Cristoloveanu says enthusiastic technical discussions continued unabated (and continued even further in follow-up emails), lots of business cards were exchanged, and opportunities for further education were explored. Day 2: Hands-on Training The second day, designers got hands-on training from Leti experts using FD-SOI PDKs, first in the morning on digital, then in the afternoon on RF. Everyone loved the lively discussion and in-depth exchanges between the experts and the designers. They agreed that FD-SOI has important applications and differentiated competitive advantages for IoT, 5G, automotive, AI and other fields. At the end of the training, Leti and SITRI jointly issued SOI Academy certificates of completion to the designers. Feedback from participants was very good. Some asked for further education and for hands-on testimonials from companies that are already designing and manufacturing products on FD-SOI. “The participants were focused, motivated, involved, with good knowledge, which helped make the three hours of Digital training effective,” said Dr. Alexandre Valentian, Leti Sr. Expert, Digital Design. “The IT team was very helpful in setting up the training, the students accounts and the hardware infrastructure.” “The training on Basics of FD-SOI RF circuit was a great success thanks to the efficiency of our Chinese partners and also thanks to the enthusiasm and the good level of our trainees. As senior Expert of CEA Leti I was really impressed by the professionalism of the organization team. For all these reasons, I’m very glad to have had the opportunity to contribute to the 2018 SOI Academy,” said Dr. Baudouin Martineau, Leti Sr. Expert, RFIC Design Technologies. “The professionalism, efficiency and enthusiasm of our Chinese partners and the level and technical relevance of all trainees made the training on Basics of FD-SOI RF circuit a great success and fruitful experience,” added Frédéric Hameau, Sr. RF Research Engineer, Leti Project Leader, Architecture, IC Design Embedded Software Division, RF Architectures and ICs Laboratory. “It was a pleasure to get the opportunity to be part of this first edition of SOI academy 2018.” The organizers would like to thank the sponsors, including: the SOI Consortium and its members Soitec, VeriSilicon, GlobalFoundries, Simgui and Cadence, as well as Mentor, ProPlus and other companies and institutions in China and worldwide. Dr. Mazure notes that special recognition must go to Dr. Julien Arcamone, EVP, Leti-CEA and to Qing Wang-Bousquet, SITRI representative, for the perfect and smooth organization, and to the Leti instructors, who are international experts and highly committed. “As one of the main initiators and organizers of the 2018 SOI Academy, I wanted to personally thank all of you for your respective contribution to this first edition of the SOI Academy,” concludes Dr. Arcamone. “Undoubtedly, it was a great success, very well organized and fluid and we can be proud of that.”
Read More
Orders for critical subsystems evaporated in the second half of 2018 after a very strong start to the year. Subsystems suppliers have been left with depleted order books after OEMs accumulated large inventories as the market for wafer fab equipment cooled off. Although overall critical subsystems revenue growth for 2018 is forecast to come in at +5% YoY, this year has been a tale of two halves with a bumpy ride for the critical subsystems supply chain along the way.The year started very strongly with overstretched OEMs switching from a “just in time” ordering strategy to panic buying and over ordering critical subsystems “just in case” as they battled to keep up with equipment demand from chipmakers. However, falling memory prices and technology push outs from major chipmakers in Q2 saw a sharp reduction in capex and demand for equipment. The whiplash effect through the supply chain has been severe and critical subsystems suppliers running at full capacity were unable to stop fast enough.Comparing inventories of vacuum processing OEMs (major consumers of advanced critical subsystems) and critical subsystems suppliers, warning signs for subsystems suppliers were apparent after the Q2 quarterly earnings reports. After OEM inventories surged in Q2, critical subsystems supplier inventories spiked in Q3. The overproduction of subsystems leading to this spike suggests that the OEMs had been promising orders to subsystems suppliers but turned off the buying as they too struggled to shift their own products earlier in the year. Suppliers of highly customised subsystems such as vacuum valves and power supplies were particularly badly hit. Whereas other subsystems such as vacuum pumps, which can generally be repurposed on other tools or applications, have fared better as the oversupply can be consumed by a wider variety of applications.The bad news does not appear to be finished for subsystems suppliers as Q3 OEM inventories as a percentage of revenue remained at historically high levels, which is a concern in the short term. Nevertheless, the underlying drivers for the industry remain strong and there is light at the end of the tunnel as major fab building projects in Asia appear to be continuing without delay – a promising sign that chipmakers are still intending to increase capacity. There will be a lot of empty fab shells and upgraded clean rooms ready for equipment installations at short notice if required, ensuring that orders for equipment and subsystems will pick up again soon. Although 2018 will appear in the historical data as a flat, if not slightly positive year, it does not quite reflect the bumpy ride that has been experienced by the supply chain along the way.For more information about VLSI Research and Critical Subsystems, visit www.vlsiresearch.com/public/csubs/. Julian West is a technical and market analyst at VLSI Research Europe.
Read More
Meeting Attended by More than 100 Tech Company RepresentativesOver the past decade, China has become a central market for the semiconductor industry. China is now home to more than 30 percent of semiconductor end users worldwide. All semiconductor companies, regardless of size, operate in China. The rise of China’s semiconductor market has been enabled by global commerce and a vast network of supply chains that span the globe.With China now a prominent player in the industry, it has become critically important for semiconductor companies to effectively engage with China. In order to help our member companies better understand the challenges and opportunities and navigate what can be a complex landscape, SEMI hosts annual trade compliance conferences in China for trade professionals. This year, SEMI, with CompTIA and U.S. Information Technology Office (USITO), hosted two global trade seminars in China, one in Shanghai on October 30th and the other in Beijing on November 1st.Over 120 representatives from more than two dozen technology companies attended the 2018 trade compliance seminars. Over the course of the two sessions, speakers from government, business, and law firms highlighted the most pressing trade issues in China. Speakers included thought leaders, trade practitioners and senior Chinese government officials.Sessions included a deep dive on China’s draft customs reform law, a panel discussion on U.S. export controls, and a briefing on how best to engage with China Customs and how China’s products are classified. Another well-received session focused on the status of China’s export control law, which has been in the drafting process for years.However, the overarching question for many attendees was U.S.-China economic relations, which are undergoing a sea change, with the U.S. having imposed or threatened tariffs on all imports from China – totaling more than $500 billion in goods – over the past six months. As a speaker noted during a session on the U.S.-China tensions and the surrounding broader geopolitical impacts, the environment is becoming increasingly complex and volatile. In fact, on the morning of the first session, Fujian Jinhua Integrated Circuit was added to the U.S. Commerce Department’s entity list, which effectively restricts exports to the company.As a result of the trade actions, ranging from tariffs to enhanced export controls, U.S. semiconductor companies are beginning to increase prices, reduce research and development (R D) budgets, restructure supply chains and take other mitigation actions that will ultimately slow innovation. Certain export controls and other regulations that prohibit U.S.-companies from conducting business with targeted companies will put the U.S. at a competitive disadvantage.In fact and as we speak, some companies with China-based operations have cancelled orders from U.S. companies and shifted to suppliers that are not subject to U.S. actions to reduce the associated risks of supply interruption and cost increases. Ultimately, U.S. trade policy could backfire, threatening jobs, curbing growth, cutting U.S. R D investments and compromising the competitiveness of U.S. firms.SEMI will begin planning next year’s Global Trade Seminar in the coming months. If you would like to be involved in the planning, or would simply like more information about the seminar, please contact Jay Chittooran, Public Policy Manager at SEMI, at [email protected].
Read More
Artificial intelligence (AI) is on the verge of transforming entire industries as it gears up to power semiconductor industry innovation and growth, thrusting the technology to front and center at SEMICON Japan 2019, December 12-14 at the Tokyo Big Sight (Tokyo International Exhibition Center).The SMART Technology Forum at SEMICON Japan will highlight the latest AI developments and trends. Supported by U.S. Commercial Service in Japan, the forum will feature Yutaka Matsuo of the University of Tokyo. An authority on AI, Matuso will give an overview of both AI business and technology. His presentation will be followed by an AI outlook from Microsoft Japan, Amazon Web Services and DefinedCrowd.A number of Japanese startups are on leading edge of AI innovation in machine and deep learning. One is Preferred Networks Inc., a company that applies cutting-edge deep learning technology to Internet of Things (IoT) applications across transportation, manufacturing and healthcare.In his opening day keynote at SEMICON Japan, Toru Nishikawa, president and CEO of Preferred Networks, Inc., will highlight the latest developments and promise of using deep learning for industrial applications. Nishikawa will unpack how AI companies jockeying for competitive advantage will win by harnessing technologies to process massive amounts of data efficiently and quickly.Following is look at Preferred Networks, Inc. and five other Japanese startups that are driving AI innovation. Within Japan's world of AI, machine learning, and deep dearning, Preferred Networks is likely the most well-known Japanese company. The parent company, Preferred Infrastructure, was founded in March 2006 by Toru Nishikawa and Daisuke Okanohara, who focused on search engine development before turning to machine learning and establishing Preferred Networks to commercialize the technology.Preferred Networks established itself as one of the world’s top providers of machine learning technology with the development of Chainer – an open source deep learning framework that has been offered free of charge since June 2015 and was released before TensorFlow, Google’s renowned Deep Learning framework. Established in 2012, ABEJA is thought to be Japan’s first venture company to specialize in deep learning. ABEJA's core technology is its AI platform ABEJA Platform. Based on this platform, the company offers various solutions to more than 100 client companies. ABEJA also offers ABEJA Insight, a specialized package service for the retail and distribution, manufacturing, and infrastructure industries. Data analytics provider BrainPad Inc. was the first Japanese AI venture listed on the Tokyo Stock Exchange. Established in 2004, before the advent of big data, BrainPad Inc. cultivated a vision of analyzing vast amounts of data in increase the competitiveness of Japanese companies. LeapMind Inc. aims to offer deep learning technology that uses fewer computing resources and draws less power. Both are important capabilities since deep learning requires considerable computing resources to perform image and speech recognition. The company’s answer to this deep learning challenge is a small form factor FPGA with low power consumption.In April 2018, LeapMind started offering the tool DeLTA-Lite to support model construction for Deep Learning. The tool simplifies the development of deep learning design models, eliminating the need for model design, hardware, and software expertise. Hacarus Inc.’s HACARUS-X AI technology, which combines sparse modeling and machine learning technology, features low power consumption and small devices such as FPGAs. In collaboration with semiconductor trading company PALTEK, Hacarus is integrating HACARUS-X algorithms with Xilinx's FPGA Zynq UltraScale + MPSoC. Both companies area also implementing HACARUS-X algorithms in a box computer.Sparse modeling is gaining attention as a modeling method by which humans can understand the judgment process of AI by extracting features from a small amount of learning data. With expertise in life science fields such as medical and biology and image processing technology, LPixel, Inc. develops image analysis systems with original algorithms and machine learning techniques. It has developed a cloud-based AI image analysis platform and an AI medical image diagnosis support technology that streamlines the review of large amounts of research data and detects image fraud in research papers and other documents for the medical and biology fields, freeing researchers to devote more time to their core work. Yoichiro Ando is a marketing director at SEMI Japan.
Read More
When developing industry forecasts, market analysts gather data from hundreds of companies to provide actionable insights on established technologies and to identify near-term business opportunities. As a developer of new MEMS and sensor technologies for a range of commercial applications, clients often ask us, “What’s going to be hot?” Gauging the promise of emerging technologies that are five to 10 years from commercialization requires taking a different tack.History tells us that most of today’s blockbuster MEMS products were born as academic research projects. Years of hard work by entrepreneurs, funded by millions of dollars, have turned proof-of-concept research into new commercial products. To identify up-and-coming technologies, we gather information straight from the source: academic conferences and articles.Chirp Microsystems is a good proof point of our research methodology: In my 2012 report on emerging technologies, I highlighted research from UC Berkeley and UC Davis on “In-Air Ultrasonic Rangefinding and Angle Estimation Using an Array of AlN Micromachined Transducers.” Soon after publication, the authors incorporated Chirp Microsystems to commercialize their technology for gesture- and fingerprint-recognition applications.After five years of development work, Chirp’s products are entering the marketplace. In February 2018, the global supplier TDK InvenSense acquired Chirp, underscoring the company’s commercial potential. At October’s SEMI-MSIG MEMS Sensors Executive Congress in Napa, Calif., Chirp’s CEO, Dr. Michelle Kiang, held attendees rapt as she described her company’s journey from startup to wholly owned subsidiary.There’s a methodThis year, I reviewed over 100 papers from top researchers presenting noteworthy technologies at the Hilton Head Workshop on Solid-State Sensors, Actuators and Microsystems. My criteria for selection were: commercial relevance; offers a solution to a known or anticipated problem; and technology game-changers. The following caught my eye: Event-driven sensors: Cleverly designed silicon MEMS that consume no power while standing by. A triggering mechanical or thermal event closes a contact within the sensor to activate its circuitry and telemetry. These sensors leverage existing fabrication methods, so they could become commercial products within five years for event monitoring and security applications. (UT Dallas, Northeastern University). Figure: 5-bit accelerometer having zero standby power. The device is open circuit until a threshold acceleration closes a mechanical contact. Source: University of Texas at Dallas. Thin film piezoelectric resonators: Advances in PZT deposition methods and process integration with CMOS were used to create monolithic acoustic waveguides for RF filtering in 5G applications. This new filter design, using existing scalable processes, is ripe for commercialization. (Purdue University, Texas Instruments) Intra-body communications: MEMS ultrasound transceivers, made from aluminum nitride, can send data directly through flesh at Mbit/s data rate. With trends toward networks of multiple implanted or wearable medical devices, this innovation would enable medically safe, secure, intra-body wireless communication. This early-stage work still needs in vivo validation and would likely require 10 or more years for development and regulatory approval. (Northeastern University) Screen- and 3D-printed sensors: One example of many exciting innovations using screen- and 3D-printing are potentiometric nitrate soil sensors. Low-cost and biodegradable, these sensors could be spread over huge areas to monitor a farm’s soil quality. Table-top and hobbyist tools are currently used to make screen- and 3D-printed devices, so new manufacturing equipment and infrastructure must be developed before commercial production could occur. (Purdue University) Biodegradable batteries: A paper-based battery that can deliver 0.5 uW of power, ingeniously using bacterial metabolism as the electrolyte. These batteries dissolve in water and could one day be used to power temporary medical implants or biodegradable sensors. This exciting proof-of-concept prototype will require significant process development and new manufacturing infrastructure for commercialization. (SUNY Binghamton) Figure: Paper-based battery dissolves in 60 minutes after immersion in water. Source: SUNY Binghamton To read more about these technologies, please download my presentation from SEMI-MSIG’s MEMS Sensors TechXpot at SEMICON West 2018.Alissa M. Fitzgerald, Ph.D., is the founder and managing member of A.M. Fitzgerald Associates, LLC, a MEMS and sensors development company in Burlingame, CA. She has over 20 years of engineering experience in MEMS design, fabrication and product development and now advises clients on the entire cycle of product development, from business and IP strategy to manufacturing operations. She is a frequent speaker at industry conferences and currently serves as a director of the Transducer Research Foundation, sponsor of the Hilton Head Workshop. She received her bachelor’s and master’s degrees from MIT and her doctorate from Stanford University in Aeronautics and Astronautics.For more information, visit: www.amfitzgerald.com
Read More
Automobiles have become an even more important segment for MEMS and sensors as carmakers integrate more chips for propulsion, navigation, and control into their designs. However, these advanced functions and their crisp rate of adoption have fragmented the sourcing of automotive chips. IHS Markit’s Jérémie Bouchaud provided a closer look at and outlook for this key market at the MEMS and Sensors Executive Congress in late October in Napa. Following are key takeaways from his presentation.Autonomous and Electric/Hybrid Vehicles to Drive MEMS Market GrowthThe automotive market, approaching 100 million vehicles produced annually, is approaching $6 billion, dominated by MEMS and silicon magnetic sensors for chassis and safety, and powertrain applications. Going forward, the market growth will be in autonomous vehicles and electric/hybrid vehicles. Because the penetration of electric and hybrid vehicles is much higher than that of autonomous vehicles, it has a larger available market, particularly for sensors. Each of these markets has its own dynamics.For example, the electric and hybrid market has historically relied on a significant number of traditional, or non-semiconductor sensors, but new sensor technologies are vying to address multiple sensing needs. The most important limitation on demand of autonomous vehicles is the overall market penetration: IHS Markit expects autonomous vehicle production to reach 10 million at most by 2030.Production of Electric and Hybrid Automobiles Now Growing at Fast ClipProduction of electric and hybrid vehicles is in a rapid growth phase, and IHS Markit expects penetration of such vehicles to reach 50% of the automotive market by 2030, up from 3% in 2016. The core functions of charging and power inversion require, among other capabilities, current, temperature and position sensing. Historically, many of these functions have been handled by non-semiconductor devices, for example negative temperature coefficient (NTC) thermistors for temperature sensing, devices that appear to be strongly positioned. In other areas, semiconductor sensors are competing with traditional devices.For example, silicon magnetoresistive devices are going head-to-head with inductive devices for position and Hall effect sensing. Sensing requirements are also likely to evolve over time, particularly as battery systems become more reliable and robust. While some automakers are looking to sensors to monitor pressure or gas leaks from batteries, battery makers are more focused on maturing the systems and reducing the need for monitoring.Autonomous Vehicles Drive New Source of Demand for MEMS and SensorsThe movement towards automated driving has created a new source of demand for MEMS and sensors, with advanced driver assistance systems driving faster growth than the historical powertrain applications. Currently available vehicles are at Level 2 (partial automation), with multiple cameras and radars. Level 3 vehicles (conditional automation) are likely to enter the market next year, adding driver monitoring cameras, LIDAR systems and, potentially, microbolometers or other night-vision systems. Level 4 and 5 (high and full automation, respectively) will add vehicle-to-vehicle communications and other systems, but are not likely to be widely available for several years.The autonomous vehicle market, while smaller overall compared to electric/hybrid vehicles, provides a more attractive opportunity for MEMS devices, particularly in LIDAR systems. LIDAR and other sensing/surveying systems are at the heart of autonomous vehicles, and MEMS devices are in demand for the critical beam-steering function. However, demand for image and other sensors will accelerate as the higher levels of autonomy are rolled out.Automotive Drives Extremely Diverse Set of Applications for MEMS and Sensor MakersThe automotive market presents an extremely diverse set of applications for MEMS and sensor makers. Some companies have developed broad product portfolios and compete in multiple applications. For example, TDK offers NTC thermistors as well as MEMS and silicon-based sensors. Semiconductor companies such as Infineon are competing in MEMS and with silicon-based sensors such as magnetoresitive and Hall effect.The growth in demand for image and radar sensors used in ADAS, as well as magnetoresistive and Hall sensors in EVs, means that the center of gravity in automotive markets is likely to shift from MEMS over the next several years – a fundamental change, Bouchaud cautioned, that will put automotive sensor suppliers focusing solely on MEMS at risk.Paul Semenza is a consultant in SEMI Industry Research and Statistics.
Read More
With (most of) the election results in from the U.S. midterms, the expected Democratic takeover of the House and the Republican’s maintaining control of the Senate is now a reality. The day of the election, DC insiders expected that the House would go to the Democrats by a margin of +/- 20, with the Republicans gaining 2-3 seats in the Senate. Not a bad prediction, which is a far cry from what the same insiders called in advance of the 2016 Presidential election.What does that mean for our members and the tech sector in general? Will there be an ease of trade tensions or less of a chance of tighter export controls? Some believe that with the midterm elections over, President Trump will have some room to take a less aggressive stance against China, setting up a “win” that he can carry into 2020. With the recent more aggressive stance by North Korea against the U.S. regarding its nuclear program, China may well have some leverage at the trade table … and the U.S. may want to make a deal that provides a path for a “win” on both fronts. Indeed, there are the makings of a potential win-win leading into the G20 meeting in Argentina when President Xi Jinping and President Trump are scheduled to meet on Dec. 1.One can see a scenario where there is a meeting of the minds and some degree of lessening tariffs; that does not mean that the effort to enhance export controls will go away. The need for tighter restrictions on export controls is driven to a great degree by the U.S. Department of Defense (DoD) and is a follow on from the previous FIRRMA legislation and attempts to curb the loss of U.S. technology critical to global competitiveness and national security. This issue will not go away anytime soon, and cases like the recent one involving Jinhua only add fuel to the fire. In addition, given how these cases can be leveraged at the negotiating table, they will continue to surface.SEMI’s approach has been to educate governments, lawmakers and administration officials on the strategic importance of the globally connected and highly complex semiconductor supply chain, and how some of the approaches will not achieve the attended goals. This approach helps to ensure that when and if it comes time to make decisions based on merit, the principals are informed. It also helps SEMI and its members develop and maintain important relationships and positions SEMI as an industry leader and spokesperson, making it a more effective advocate. As an example, on Nov 8th SEMI released its Global Trade Principles with the intention of providing a framework to all governments to guide various trade talks. It also helps to inform member companies and others from the broader tech sector of our industry position(s) so we are able to speak with one voice. These principles are aligned with our fundamental advocacy pillars of promoting free trade and market access, respect for IP, cybersecurity and national security.Will the fact that power is now split between the two chambers of Congress help or hurt? Will the House focus on investigations limit the ability to move productive legislation? Besides taking time, it may well put them at increasingly worse odds with the Senate and the President (if that is possible), creating deadlock. Some argue that if nothing moves, no harm can be done. Some also say that it may drive the President to take independent and more aggressive actions in order to demonstrate (his) effectiveness to his base. There is another view: that with the Democrats, the President may be able to lead in the advancement of legislation that will show he can get things done when others couldn’t in areas that benefit the greater good…some of which may impact our industry…such as investments in education and infrastructure development. This would be a way that he could pull in some of the votes from the middle that he has lost in his first two years in office. They say “politics makes for strange bedfellows”; one never knows what might happen in this case.Regardless of what happens, some things will not change: the global nature of our business and the needs of our members to have access to markets…and to be able to safely and efficiently leverage their technologies in the way they see fit in order to grow their business. SEMI will continue to advance the interests in what is an extremely challenging and dynamic global policy environment today. As ruling parties and representatives change around the globe, we will continue to build new relationships and educate lawmakers so they are able to make informed decisions that benefit our members. Mike Russo is VP of Public Policy and Talent Advocacy at SEMI.
Read More
Lots of great information came out of the two days of workshops in Japan recently organized by the SOI Consortium. Some of the presentations are now posted on the consortium website (get them here). The first day (held in Yokohama and sponsored by Silvaco) focused on FD-SOI and RF-SOI design. The second day (held at U. Tokyo) focused on More than Moore (especially silicon photonics, MEMS sensors), and the SOI manufacturing ecosystem. The 1st day panel discussion was so interesting we'll give it a post of its own, then follow up with round-ups of the presentations from both days. And now to ramp! The morning panel discussion on end-user deployment for FD and RF-SOI was moderated by SOI Consortium Executive Director Giorgio Cesana. GF's CTO Subi Kengeri led off saying that that 2017 had been the year of FD-SOI adoption. Samsung Director Adam Lee noted that in the beginning nobody believed it would get traction, but now everybody does, and Samsung is commercializing it: chips coming out this year will ramp in volume in 2019. [caption id="attachment_12578" align="aligncenter" width="875"] Panel on FD-SOI and RF-SOI end-user deployment, SOI Workshop Japan, 2018. Giorgio Cesana, SOI Consortium Executive Director, Moderator; John Carey, ST Director; Adam Lee, Samsung Director; Subramani Kengeri, GF CTO; Wayne Dai, VeriSilicon CEO; Mostafa Emam, Incize CEO. (Courtesy: SOI Consortium)[/caption] VeriSilicon CEO Wayne Dai said he sees great potential in IoT, where the volumes are high but fragmented. In IoT, he said, you need RF, but you really only need very high performance about 20% of the time, which is a perfect fit for FD-SOI. ST Director John Carey noted that ST's been using FD-SOI since 2014. They've fabbed products for cryptocurrency and infrastructure. Now in their second and third generations of designing with it, they've got some big FD-SOI chips coming out next year with embedded memory and RF. He sees it being particularly successful in mmWave, automotive and IoT. The conversation then shifted to RF-SOI. Mostofa Emam, CEO of Incize, explained that since RF-SOI is already in every smart phone, it's in a different situation from FD-SOI. The emphasis here is now on adding more blocks. “RF is an art,” he said. “It takes an artist. You need talented artists and tools.” One of the biggest challenges for fabs that are newcomers is models – not just at the transistor level, but also at the substrate level. The big players have addressed this, but Incize is working to support more foundries with new, innovative approaches, and helping them develop robust PDKs. The industry needs more good RF designers as well as better RF design flow, he concluded. Coming back to FD-SOI, Cesana asked about non-volatile memory (NVM). Samsung's Lee said they've already got NVM options including eMRAM for 28nm, and customers are now requesting eMRAM PDKs for the next node (18FDS). ST's Kengeri added eNVM is important for FD-SOI, especially since flash is not scaling. While there are lots of options, MRAM gives you all the value, and in FD-SOI it only adds three more mask steps, so cost savings are maintained. With respect to local computing for AI with FD-SOI, everyone agreed on the importance of the edge. In addition to RF, FD-SOI gives you density even at 28nm, explained Carey. You can manually control power with back biasing, so you get something very flexible, especially for NB-IoT applications where the battery will have to last for 10 years. In fact Kengeri sees FD-SOI as enabling fog/edge computing. 5G – What's First? The next question was about 5G: which applications would we be seeing first, and how does FD-SOI help? Lee said Samsung's seeing it for apps up to 10GHz as well as mmWave. Customers are telling them they want FD-SOI for technical reasons. Kengeri expanded on that point, saying it comes down to fundamental physics: gate resistance, capacitance, mismatch. FD-SOI has lower Vmin and better Fmax compared to FinFETs, and that's what tier-one players want. Carey brought it back to RF-SOI (noting that ST's introducing a 45nm version), which supports a large number of elements and increased complexity with smaller power budgets. Emam then asked the foundry guys about mmWave. Substrates won't be the bottleneck he said, so what's the FD-SOI/mmWave roadmap? Kengeri responded that GF's ready. Lee said Samsung is also ready, and you'd see it next year on handsets. Samsung has engaged with customers on 30GHz for the middle of next year, he added: it's qualified. Carey said ST sees it first in consumer premises equipment that's connected by satellite. The right enabler Cesana then asked about image sensor processors (ISPs), noting that analyst Handel Jones has said this is a big opportunity for FD-SOI. You can do 3D integration with sensors, but heat makes noise, so you need technology that decreases heat production and doesn't give you hotspots (which would be visible in the image). Kengeri pointed to challenges in power density, thermal envelopes and the RTS (random telegraph noise signal). Although there are a lot of options, FD-SOI plays well for thermals and noise, so GF sees a good opportunity here. Dai added that the industry needs volume applications for FD-SOI, and ISPs need to bring more logic closer to the camera. And he concurred that you need FD-SOI for the thermals: it's very important. In closing, Dai noted that as a design house, “We walk on two legs: FinFETs and FD-SOI.” 28, 22, 18 and 12nm FD-SOI all enable differentiation. In particular, you need something between 20nm and 7nm: FD-SOI is here. Asked about Japan in particular, Dai said beyond automotive he saw lots of potential in ULP for AVR. Kengeri added that for any applications besides performance-at-any-cost, FD-SOI is the right enabler.
Read More
Kyushu, the third largest island in Japan, is home to the semiconductor production bases of integrated device manufacturers (IDMs) with world-class cutting-edge technology. SONY, Toshiba, Hitachi, Mitsubishi, Fujitsu and Nissan are among the sector’s shining stars, though a host of other IDMs tied to the supply chains of other major enterprises have also set root in Kyushu. Collectively, the companies earned Kyushu the name Silicon Island of Japan.Kyushu’s flourishing IDM industry sprouted from favorable tax and other government policies that reduced semiconductor production costs to levels lower than elsewhere in Japan. Once the IC producers had established bases, equipment and materials companies naturally followed, leading to the influx of many parts manufacturers. Together, they came to Kyushu, one after another, to make the island a magnet for manufacturing. And so it was to Kyushu that a SEMI China delegation travelled for a meeting at TEL’s factory in Kumamoto to learn more about the secrets to the rapid growth of the island’s semiconductor industry and promote cooperation between Chinese and Japanese enterprises. Underscoring the rise of the Silicon Island of Japan, China will soon become TEL’s largest market, said Masami Akimoto, Chairman of Tokyo Electron Kyushu Limited, speaking at the event. Masami Akimoto hopes for support from SEMI China.The island of 12 million people contributes to the growth of the global semiconductor industry, expected to reach USD 500 billion in size in 2019 as China’s semiconductor sector, fueled in part by government-backed investment funds, continues its rapid expansion. Despite the gains, China still lags other regions in advanced manufacturing, said Lung Chu, president of SEMI China, which is doing its part to draw more advanced manufacturing to the region through its SIIP platform. The initiative encourages pan-regional cooperation with China’s semiconductor industry to promote free trade, open markets, technology innovation and IP protection – all to help China better integrate with the global semiconductor industry. SEMI China President Lung Chu(L) issues visit memorial to Masami Akimoto(R), Chairman of Tokyo Electron Kyushu Limited. Chicken shall be led by the HenUnlike other regions with comprehensive semiconductor industries, Kyushu’s is primarily focused on production and assembly, with more than 200 manufacturers of semiconductor equipment and parts.SEMI China Delegation at Tokyo Electron Kyushu LimitedTEL built its first factory in Kumamoto, a city covered by volcanic ash in the center of Kyushu, 34 years ago. Today, TEL every month produces 80 to 90 sets of equipment, each consisting of, on average, over 400 thousand parts that must be certified and authorized by TEL before delivery to its module manufacturers and assembly into complete machines. Having blossomed over the past few decades, the island’s supply chain now supplies TEL with all its equipment parts. SEMI China Delegation at Fajita WorksTEL supplier Fajita Works, a high-precision plate metal manufacturer founded in 1945, is emblematic of other companies in the Kyushu supply chain. It keeps a low public profile as it serves several longtime customers and earns ardent loyalty from its workers, an ethos reflected in the change next January of its slog from “Only One” to “Great company, Great life.”Quality is the life of the enterpriseLong before the rise of its legendary automobile and consumer electronics companies, Japan was known for inferior, counterfeited products, labeled “Made In USA” and shipped to the United States by more than 100 factories. The net effect was to shrink and commoditize American markets. The tide in Japan’s product quality and stained reputation began to turn in the 1980s, when Japan’s semiconductor industry began to produce memory with an error rate 27 times lower than its U.S. competitors, giving Japan an upper hand in quality that it would never relinquish. SEMI China Delegation at HORIBAKyushu-based flowmeter supplier HORIBA, among the many Japanese companies famous for their product quality, ships 38 percent of its products into the automotive market and 27 percent into the semiconductor sector. Cleanliness is as vital a part of the company’s culture as quality. Each depends on the other, with fine detail held to the highest importance. On its visit to HORIBA, the SEMI China delegation, passing by an office area before entering the factory, sighed at the sight of the spotless, neatly kept furniture and workspace: They had never seen an office so sparkling clean. HORIBA’s success is rooted in immaculate offices, factories and the company’s motto “Enjoy innovation and pay close attention to product quality.”After Kumamoto sustained heavy damage during a 2016 earthquake, HORIBA workers returned rocks scattered by temblor to their original position, knowing that order is critical to lean, efficient manufacturing and that, indeed, “the devil is in the details.” SEMI China Delegation in Kumamoto City Full confidence in the exploration of Chinese marketConsumer electronics stalwarts Sony and Panasonic feature semiconductor factories in Kagoshima, the southernmost city in Kyushu and Japan, though rumor had it two years ago that Panasonic planned to pull out. The Panasonic plant, which provides batteries for Tesla, remains. The Sony facility produces image sensors for the iPhone.Semiconductor equipment maker ULVAC, SEMI China’s most important strategic partner, is also based in Kagoshima. During the delegation’s visit to the company, Lung Chu noted that while China is the world’s largest semiconductor market, the region meets just 13 percent of domestic chip demand. Stressing that ULVAC can play a crucial role in helping China become a bigger player, he expressed admiration for ULVAC’s professionalism along with hope that it will maintain its rapid growth and leverage SEMI resources to catalyze rapid development of Internet of Things (IoT), artificial intelligence (AI), and 5G technologies in China and rise into the top 10 of global equipment manufacturers. SEMI China President Lung Chu (L) issues visit memorial to ULVAC Kyushu President and CEO Kenji Yamaguchi ULVAC Kyushu president and CEO Kenji Yamaguchi made clear the company’s interest in Lung Chu’s insights into Chinese semiconductor industry while underscoring its core competency of producing semiconductors for flat panel displays. The Kyushu Factory of ULVAC is full of vitality and market competitiveness. SEMI China Delegation at ULVAC EBARA, a precision machinery company located in Kumamoto, has manufactured chemical-mechanical planarization (CMP) equipment for over 20 years and delivered nearly 2,400 mechanical polishing machines worldwide. While the company expects to ship 50 sets per year to China starting next year, it has the capacity to deliver 20 sets per month, enough to meet demand of Chinese semiconductor makers. SEMI China Delegation at EBARAThe most telling takeaway from the SEMI China delegation’s visit to the Kyushu: Japan ranks number one worldwide in research and development (R D) investment as a proportion of GDP and is also at the top in the percentage of R D funds controlled by private enterprises. The outsize investment strategy has enabled Japan to maintain its hold as one of the world’s top technology innovators.Like Sakurajima, the famed Kyushu volcano, the SEMI China delegation will continue to harness its forces to build relationships with the island’s semiconductor supply chain as it works to develop win-win pan-regional relationships and foster the growth of China’s semiconductor industry. Best view of Sakurai volcano Gang Yao is a marketing director at SEMI China.
Read More
Since about a third of all IoT devices are expected to be connected by Bluetooth, chip designers need IP solutions that will help reduce system cost and greatly improve battery life. And that's just what VeriSilicon has announced for GlobalFoundries' 22FDX® (FD-SOI) process. “By taking advantage of integrated RF capabilities of FD-SOI, in particular GF’s 22FDX, our BLE 5.0 RF IP will significantly reduce the system cost and greatly boost the growth momentum of wearable products such as wireless earplugs,” said Dr. Wayne Dai, Founder, Chairman, President and CEO of VeriSilicon. 22FDX enables efficient single-chip integration of RF, transceiver, baseband, processor, and power management components. GF and VeriSilicon are working on an SoC using VeriSilicon's BLE 5.0 RF IP in GF’s 22FDX process. The latest iteration of Bluetooth is 5, which (like its predecessor 4) has a Low Energy (LE) RF option – but with big improvements. According to the Bluetooth website, “With 4x range, 2x speed and 8x broadcasting message capacity, the enhancements of Bluetooth 5 focus on increasing the functionality of Bluetooth for the IoT.” BLE 5.0 was designed for very low power operation and is optimized for the sorts of short burst data transmissions you'll get with IoT. On the strength of VeriSilicon’s innovative RF architecture and by leveraging GF’s 22FDX technology, VeriSilicon says the new IP product achieves significant improvements in power, area, and cost compared to current offerings, so it will better serve the emerging and increasing wearable devices and IoT applications space. "VeriSilicon's BLE IP complements GF's 22FDX FD-SOI capabilities and is well positioned to support the explosive growth of low-power IoT and connected devices," said Mark Ireland, vice president of ecosystem partnerships at GF. "Together, we broaden our IP and services to further enable our mutual clients to provide power and cost efficient solutions." VeriSilicon BLE 5.0 RF IP includes a transceiver that is compliant with the BLE 5.0 specification and supports GFSK modulation and demodulation. The silicon measurement shows that the sensitivity can be tested up to -98dBm with less than 7mW power dissipation in typical conditions. It largely improves battery life for low power IoT applications. In addition, the RF transceiver saves 40% area compared to a similar implementation on 55nm bulk CMOS. Besides the RF transceiver, this IP integrates on-chip balun, TX/RX switch and 32K RC OSC driver to save the BOM. Moreover, high efficiency DC/DC and LDOs are also available for power management. You can read the full press release in Chinese here and in English here.
Read More