downloadGroupGroupnoun_press release_995423_000000 copyGroupnoun_Feed_96767_000000Group 19noun_pictures_1817522_000000Member company iconResource item iconStore item iconGroup 19Group 19noun_Photo_2085192_000000 Copynoun_presentation_2096081_000000Group 19Group Copy 7noun_webinar_692730_000000Path
Skip to main content
Between January and July 2026, Stanton Chase developed three regional Semiconductor Spotlight reports focused on market dynamics and executive leadership imperatives. The research found that North America, EMEA, and Southeast Asia are all facing engineering and leadership talent shortages.The Semiconductor Bottleneck is Moving from Lithography to Advanced PackagingThe semiconductor industry is growing rapidly. Currently, IDC is forecasting that global semiconductor revenue will reach $1.29 trillion by the end of 2026, representing more than 50% growth over 2025. A separate McKinsey report takes a wider measure of the industry than sales alone, accounting for in-house design teams in its projections. On this wider measure, the semiconductor industry is projected to reach $1.6 trillion by 2030 under McKinsey’s base-case scenario.These revenue gains are being spent on innovations in memory and advanced packaging to help address the memory wall. IDC identifies high bandwidth memory (HBM) as the primary constraint in the AI accelerator supply chain. However, most HBM capacity is pre-committed through 2026, with forward allocations reaching into 2027. With strained capacity around the world, IDC does not expect any meaningful new supply before late 2026 at the earliest. Companies wanting to circumvent capacity limits must build their own facilities, but this requires experienced operations leaders.Why Semiconductor Subsidies Cannot Buy Packaging and Yield ExpertiseGovernments around the world have tried to solve the capacity shortage with public money. McKinsey’s analysis of the New Industrial Policy Observatory tracker noted a roughly 390% growth in industrial-policy actions between 2017 and 2024, listing defense, semiconductors, and high-end equipment as the focus.Government investments also go where skills are thinnest. For example, Deloitte found that expertise in back-end steps like molding and bumping is scarce in the United States and Europe. These are the two regions spending the most on bolstering their industries, and subsidies are quickly funding new packaging lines. Although facilities investments are being made, engineers who can ensure the success of these lines have typically been trained over decades. As it stands today, there are not enough skilled senior engineers to staff new buildouts.How Semiconductor Talent Shortages Differ Across North America, EMEA, and Southeast AsiaThe U.S. is rebuilding the manufacturing infrastructure that was moved offshore after the year 2000. Section 48D, a manufacturing investment tax credit to incentivize domestic semiconductor production, now offers a 35% investment credit for advanced manufacturing facilities, up from the 25% rate set in 2022. The higher rate applies to qualifying property placed in service after 2025, and the credit does not apply to projects whose construction begins after December 31, 2026.Although this incentive is large, the country’s workforce is not in place to staff new manufacturing sites. McKinsey’s 2024 labor analysis stated that the U.S. semiconductor manufacturing workforce was down 43% from its peak in 2000. While around 1,500 engineers join the semiconductor workforce each year, forecasts show demand for 88,000 new engineers by 2029.Europe’s shortage runs the other way. While the U.S. lacks engineers it never trained, Europe is losing its engineers to retirement. The European Court of Auditors highlighted that the EU’s 20% output target is very likely to go unmet and cited skilled worker shortages among the factors affecting implementation. The European Chips Skills Academy, coordinated by SEMI Europe, reported that nearly 30% of the European semiconductor workforce is expected to retire by 2030. At the same time, graduate inflow is rising by less than 1% each year.Furthermore, Southeast Asia trains a high volume of engineers, but some Southeast Asian countries struggle to keep them. Malaysia’s deputy trade minister noted that of every ten graduates trained, only three remain in the country after a few years. Those engineers typically move within Southeast Asia rather than out of it, but they move to Singapore, where pay is better. While Singapore represents 10% of the global chip market, it also struggles with an aging workforce. To keep pace with its demand, Singapore recruits from neighboring countries.Every Regional Semiconductor Facility Competes for the Same Talent PoolEven though each region is specializing in something specific, all of them are recruiting the same engineering experts. For example, Deloitte expects Southeast Asia and India to grow as hubs for high-volume, back-end manufacturing. Meanwhile, Taiwan, the U.S., Japan, and parts of Europe are furthering heterogeneous integration and advanced packaging innovation. Deloitte concludes that talent constraints in advanced packaging may hold back regional autonomy goals around the world, even as back-end capacity keeps expanding in Asia.Every program described exists to move advanced production out of Asia; however, the only people who have run advanced production at scale are in Asia. Public money can pay for a fab, but it cannot produce an experienced operator. This forces each region to compete for the same small group. For instance, hiring an engineer in the U.S. removes them from Taiwan.What Semiconductor Leadership Planning Should Look Like Before 2030To adequately staff new facilities and meet rising demand, hiring decisions must be made before 2030. Chipmakers that fill senior plant and engineering roles on time do so by planning for new hires years in advance rather than waiting until someone resigns. Companies that hire successfully also benchmark pay against Taiwan and South Korea and allocate enough budget for relocation.This article summarizes the key findings of the three Semiconductor Spotlight reports and their shared talent development roadblocks. Each white paper covers its own region in depth, outlining where investments have been committed and the roles that need to be filled.Read each report to learn more.Semiconductor Spotlight: North AmericaSemiconductor Spotlight: EMEASemiconductor Spotlight: Southeast AsiaAbout the AuthorJan-Bart Smits is managing partner at Stanton Chase Amsterdam, global sector leader for technology, and global subsector leader for semiconductors. In his more than 30-year career, his work has taken him across semiconductors, technology, and professional services, and his earlier global roles at Stanton Chase included global practice leader for professional services and global chair. He contributed to each of the three regional Semiconductor Spotlight reports and holds a master’s degree in astrophysics from Leiden University.
Read More
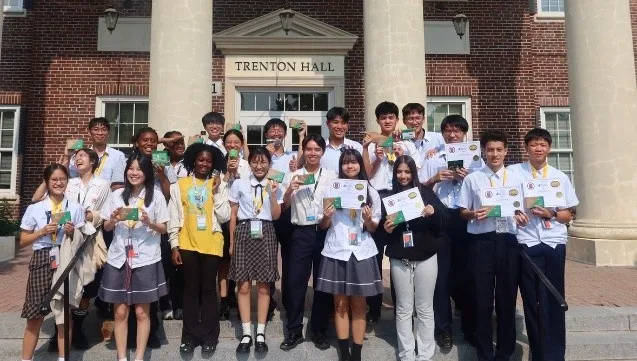
This summer, the SEMI Foundation brought together 16 high school students from Taiwan and four students from Pennsylvania for the inaugural SEMI Global Schools Academy, a five-day learning experience connecting sustainability, emerging technology, semiconductor careers, and global collaboration.The Academy is one part of the broader SEMI Global Schools model. Classroom and school-based programs give students opportunities to explore semiconductors, sustainability, artificial intelligence, and related careers where they already learn. The Academy builds on that approach by giving a smaller group of students a deeper opportunity to learn across institutions and communities.Students used Micro:bit sensors and AI-driven data analysis to explore environmental challenges including air quality, flooding, wastewater, and sea-level rise, with hands-on activities ranking among the most highly rated parts of the Academy.Following the Academy, nine in 10 participating students reported interest in the semiconductor industry—an encouraging indication that meaningful exposure can help young people see possibilities they may not have previously considered. Connecting Institutions Across BordersWhat made the Academy possible was not a single organization or campus, but a network of institutions working together.In Taiwan, schools, educators, government partners, and advisers helped prepare and support the participating students. In the United States, universities, local governments, educators, community organizations, and industry partners contributed expertise and learning opportunities.SEMI Global Schools serves as a connector across that ecosystem, bringing together institutions that already have strong relationships with students, communities, technology, and the semiconductor industry.That approach also makes the model adaptable. Rather than creating something entirely new in every region, Global Schools can build on the schools, universities, government partners, community organizations, and companies already there.Learning Through Technology, Sustainability, and CommunityStudents began their week at The College of New Jersey, where a sustainability professor from the New Jersey Institute of Technology (NJIT) introduced climate change, systems thinking, and the United Nations Sustainable Development Goals.Throughout the week, students explored artificial intelligence, semiconductors, sensors, coding, micro:bits, environmental monitoring, and data. They considered how technology might help address real-world challenges involving air quality, energy, transportation, infrastructure, and community well-being.The goal was not to turn students into semiconductor experts in five days. It was to help them understand that the technologies they use every day are connected to a much larger ecosystem—and that there are many different ways to participate in it.Students also learned that the semiconductor workforce extends beyond engineering to areas including sustainability, data science, supply chain, business, communications, education, public policy, and workforce development.Learning Beyond the ClassroomThe Academy also gave students opportunities to experience that ecosystem firsthand.Students learned at The College of New Jersey and the New Jersey Institute of Technology, participated in outdoor environmental learning at the New Jersey School of Conservation, visited Princeton University, and engaged with technology and semiconductor professionals.They also interacted with Princeton Mayor Mark Freda and Chester Mayor Stefan Roots, connecting their learning to broader conversations about education, technology, workforce development, and community opportunities.Just as importantly, Taiwanese and American students worked together throughout the week, sharing perspectives, solving problems, and learning across cultural and language differences.Building on What Already WorksThe Academy is one part of a broader Global Schools model that also includes classroom and school-based programs. Those programs can reach students where they already learn, while experiences like the Academy provide a deeper opportunity to engage across institutions and communities.The inaugural Academy offered an early example of what that model can look like: students from Taiwan and Pennsylvania learning together about sustainability, AI, semiconductors, and community challenges while engaging universities, industry, educators, and civic leaders.As the semiconductor industry grows globally, helping young people understand that ecosystem earlier matters.That is the vision behind SEMI Global Schools: connect strong institutions and create meaningful opportunities for more students to see where they might fit in the technology workforce of the future.As the semiconductor industry expands, workforce development, education, community capacity, and strong local institutions will increasingly be part of the infrastructure that supports sustainable growth.Learn more about the SEMI Foundation and SEMI workforce development programs addressing the global semiconductor industry’s talent gap.AcknowledgmentsDr. Prabhakar Shrestha, Assistant Director of Sustainability, New Jersey Institute of TechnologyRandall Solomon, Executive Director, Sustainable Jersey for Schools The New Jersey School of ConservationMelissa Taggart, Senior Director, Project Learning Tree Development and StrategyMary Westlund, Manager, Education Systems, Project Learning TreeBia Hamed, Ph.D., is Program Manager, Global Education Initiatives at the SEMI Foundation, Dr. Yi-Hsuan (Tim) Hsu is Adjunct Professor at National Tainan University in Taiwan, and Justin Harris is Senior Advisor for Climate Equity Social Impact at SEMI.
Read More
The European Chips Diversity Alliance (ECDA), a European Union-funded initiative coordinated by SEMI Europe, hosted the third Inclusive Chips Forum Bratislava: Bridging Education and Industry for Inclusive Talent at the Faculty of Electrical Engineering and Information Technology of the Slovak University of Technology in Bratislava on September 2, 2026. Co-organized with ECDA project partner Comenius University in Bratislava, the forum brought together educators, industry representatives, policymakers, and researchers to explore how collaboration between academic institutions and employers can open the semiconductor sector to a broader, more inclusive talent pool.The event addressed questions at the heart of Europe's semiconductor ambitions: how universities and employers can work together to attract and retain talent that is too often overlooked, what role institutional culture and leadership play in creating genuinely inclusive environments, and which models of cooperation are already proving effective across Europe and Slovakia. Through presentations, panel discussions, and exchanges of good practice, participants explored concrete approaches to building pathways into the semiconductor sector for people with a wide range of backgrounds and experiences. “Europe's semiconductor future depends on its ability to draw on the full depth of its talent,” said Cassandra Melvin, Senior Director, Business Development and Operations at SEMI Europe. “That means breaking down the barriers between education and industry, and making sure that the people who have historically been left out of this sector have a real path in."The program featured perspectives from across the ecosystem: from the counselling and psychological support systems that help students with diverse needs thrive in higher education, to the sharp decline in female enrolment at technical schools over recent decades, to what it means to build a semiconductor workforce that extends well beyond engineering. A closing panel, Connecting Education and Industry to Build Inclusive Semiconductor Talent, brought together representatives from SEMI Europe, the Czech and Slovak Semiconductor Centers, and onsemi Slovakia to discuss successful models of talent development and how education can better respond to the needs of a rapidly evolving sector.“Bringing educators and employers into the same room is necessary, not just useful,” said Janka Kottulová, Project Manager at Comenius University in Bratislava and co-organizer of the event. “The semiconductor sector cannot build the workforce it needs without universities and industry designing that future together, and forums like this one are where that work begins." SEMI Europe thanks the Slovak University of Technology in Bratislava, the Slovak Chips Competence Centre, and Comenius University in Bratislava for their partnership in organizing the Forum, with special thanks to Andrea Fábiková and Janka Kottulová for coordinating the event and its program.The Inclusive Chips Forum Bratislava is part of a series of events organized under the ECDA project, bringing together stakeholders across Europe to advance inclusion in the semiconductor sector. Information on upcoming forums will be announced shortly.About the European Chips Diversity AllianceThe ECDA is a collaborative initiative comprising 11 partners across Europe. ECDA works to expand access to training and employment in microelectronics by removing barriers for underrepresented and underserved communities, helping unlock the full spectrum of Europe's talent pool. Learn more at diversityinchips.eu or follow us on LinkedIn or Instagram. Frequently Asked QuestionsWhat is the Inclusive Chips Forum?The Inclusive Chips Forum is a series of public events organized by the ECDA bringing together educators, industry representatives, policymakers, and researchers to explore how diversity, equity, and inclusion can strengthen Europe's semiconductor talent pipeline. Each forum is hosted in a different European location and focuses on practical approaches to building more inclusive pathways into the sector.What topics were covered at the Inclusive Chips Forum Bratislava?The forum covered a wide range of topics, including inclusion practices in universities and companies, counselling and psychological support as tools for inclusion in higher education, gender representation in technical schools, diverse career pathways into the semiconductor sector beyond engineering, and how education and industry can collaborate more effectively to attract and retain underrepresented talent.Who attended the Inclusive Chips Forum Bratislava?The forum brought together educators and education managers from higher education and vocational training institutions, HR professionals and company representatives from the semiconductor sector, policymakers, and researchers from across Slovakia, Czechia, Austria, and wider Europe.How can educators and industry representatives get involved with ECDA?Organizations and individuals can engage with ECDA through its events, training programs, and online resources at diversityinchips.eu. ECDA welcomes participation from academic institutions, companies, and public bodies across Europe committed to building a more inclusive semiconductor workforce.When is the next Inclusive Chips Forum?Information on the next Inclusive Chips Forum will be announced shortly. Follow ECDA on LinkedIn and Instagram or visit diversityinchips.eu to stay up to date.Marta Scandella is Communications Coordinator for EU Projects at SEMI Europe.
Read More
The SEMI Quality Benchmark Consortium (QBC) met August 19–20 at Texas Instruments (TI) in Dallas, bringing together quality leaders from across the semiconductor industry to benchmark best practices and address common manufacturing challenges.Fern Yoon, VP of World Quality at Texas Instruments, hosted the latest face-to-face meeting, bringing together representatives from Infineon Technologies, STMicroelectronics, NXP Semiconductors, GlobalFoundries, and Intel Corporation for two days of technical discussions, benchmarking, and knowledge sharing.The QBC operates on a "give-to-get" philosophy, with members contributing survey data and participating in open discussions to build a shared library of industry best practices. This meeting centered on three topics: audit programs, failure analysis, and multi-source fab qualification.The office of Jack Kilby, inventorof the Integrated Circuit in 1958The meeting opened with an overview of Texas Instruments' business, global manufacturing footprint, and quality organization. Attendees also had the opportunity to tour Jack Kilby's historic office, offering a glimpse into the legacy of the co-inventor of the integrated circuit and the innovations that helped shape the semiconductor industry. Benchmarking Audit Programs and Quality SystemsThe first benchmarking session focused on internal audit programs and quality management systems. Participants compared how their companies qualify auditors, structure audit organizations, and comply with quality management standards. The discussion also covered supplier audits, management reviews, customer audits, and ways to improve audit effectiveness while reducing duplicate effort. Sharing Best Practices for Failure AnalysisThe second session focused on Electrical-Induced Physical Damage (EIPD), Electrical Overstress (EOS), and No Trouble Found (NTF) investigations. Participants compared failure analysis workflows, stress testing methods, customer communication practices, and criteria for closing investigations. Strengthening Multi-Source Fab QualificationWith manufacturers continuing to expand production capacity, multi-source qualification remains an important priority. Members compared strategies for technology transfer, risk assessment, customer communication, and qualification planning to demonstrate equivalent manufacturing capability across multiple fabs.Looking AheadThe meeting concluded with an update from the AI Product Quality Working Group, which is finalizing a white paper on AI-enabled Failure Mode and Effects Analysis (FMEA). Members also identified future benchmarking topics, including traceability, maverick lots, and quality at speed.Through open benchmarking and knowledge sharing, the SEMI Quality Benchmark Consortium continues to help members strengthen quality systems, improve manufacturing performance, and advance semiconductor quality across the industry. The consortium will continue its work at the upcoming meeting to be hosted by NXP in Eindhoven. Front row (left to right): Fern Yoon (Texas Instruments), Sumitra Sukumaran (Intel), Jens Luepke (Infineon), Lou Cerra (NXP), Roberto Lissoni (STMicroelectronics)Back row (left to right): Karim Somani (SEMI), Mark da Silva (SEMI), Eamonn McGovern (Intel), Mark Mason (Texas Instruments), Joe Beyer (NXP), Paul Tiner (Texas Instruments), Ivo Clerici (GlobalFoundries), Wesley Hirsch (TI)
Read More
The SEMI Startups for Sustainable Semiconductors (S3) program has announced 12 startups chosen as finalists for pitching to the industry at SEMICON West 2026 in San Francisco, California. The finalists were chosen from a field of 33 semifinalists after a virtual pitch event held over two days on July 29 and 30. Startups were evaluated by the organizing committee on five factors: the sustainability impact on our industry, commercial viability of product, company value proposition, the quality of the pitch and the startup team.The committee, made up of experienced Corporate Venture Capitalists (CVCs) from the global semiconductor industry and chaired by Micron, received submissions across four categories identified for 2026:Decarbonized Semiconductor ManufacturingDesign for Sustainability – Chips PackagingDatacenter Efficiency in Power Delivery and ThermalsNew Frontiers in Sustainable ComputingNow in its fifth year, the program is built around two strengths: exposure to semiconductor industry CVCs and the personal mentoring each startup receives. Mentoring topics are tailored to align with the greatest need of the startup and can range from a basic introduction to semiconductor manufacturing to connections with new funding sources. A full analysis of the program is available here.This year’s cohort spans six countries across four continents. The 12 finalists bring solutions across abatement, thermal management, water reuse, wafer inspection, power delivery, simulation, advanced packaging and memory architecture.The SEMI Startups for Sustainable Semiconductors pitch event will take place on the Sustainability Pavilion Stage on Wednesday, October 14, starting at 1:00 p.m. Andrew Byrnes, Director of Venture Capital for Artificial Intelligence at Micron Technology and chair of the S3 steering committee, will open the session and introduce the startup pitches.The finalist pitches will run through the afternoon, with each presenter given a 10-minute slot. Halfway through the pitch order, I will host a fireside chat with Steven Bakota, Corporate Vice President, Corporate Strategy and Corporate Development at Micron. The conversation will cover the role of startups in semiconductor sustainability and how they can build strong partnerships with large fabs.After the second group of pitches, votes for the winning startups will be tabulated during the S3 alumni panel, where past participants will inspire this year’s finalists with their stories of building partnerships in the semiconductor industry. An awards ceremony at 4:05 p.m., sponsored by Pangaea Ventures, will wrap up the S3 event and kick off the Sustainability Reception.Investors are welcome to attend the session at SEMICON West and to register their interest here to learn more about the 2027 program.2026 S3 FinalistsListed in presentation order.Rise Technology srlMilano, Lombardy, ItalyRise Technology develops next-generation semiconductor equipment based on its proprietary Dynamic Drop™ technology, overcoming the limits of conventional electroplating. The platform enables high-uniformity, high-throughput formation of interconnects, improving yield and enabling advanced architectures in heterogeneous integration, including chiplets, DRAM stacking, and 2.5D/3D packaging.KoolMicro, Inc.Dongtan, Gyeonggi-do, South KoreaKoolMicro is engineering the “Thermal Highway” for the AI era. The company develops Integrated Manifold MicroChannel (IMMC) modules that handle 4,000W and higher thermal loads. Its Direct-to-Chip solution uses vertically sprayed coolant to remove heat directly from the chip level, ensuring next-generation GPUs and CPUs never throttle.VEIR, Inc.Woburn, MA, USAVEIR develops superconducting power solutions, including cables and supporting infrastructure, from grid to rack.IWI Australia Pty LimitedSydney, NSW, Australia IWI Australia has developed and piloted a patent-pending catalytic quench of hydrogen peroxide in fab wastewater, particularly in complex water matrices with high peroxide load, extreme acidity and heavy metals. The company has also developed a patent-pending oxidation process for triazole, another pain point in fab operation and water reuse.enaDyneLeipzig, Saxony, GermanyenaDyne builds a fully electric, modular abatement system for semiconductor fabs based on non-thermal plasma catalysis. Its reactor destroys PFCs, VOCs, and NOx at greater than 99% destruction and removal efficiency through electron-impact chemistry at near-ambient temperature, fitting the same footprint as burn-wet for direct drop-in replacement. The same hardware extends to electrified chemical synthesis.Powerlattice Technologies Inc.Phoenix, AZ, USAPowerlattice has developed the first true monolithic integrated voltage regulator designed for high-wattage ASICs and XPUs operating above 1kW.UNISERSZurich, Canton of Zürich, SwitzerlandUNISERS has developed a novel wafer defect inspection and characterization technology to help fabs find and identify minute contaminants below 10nm, which are mostly invisible to currently used inspection equipment. As transistor nodes move to 3nm and below, these very small particles cause significant yield issues in state-of-the-art wafer fabs.CHIPADD, Corp.Binghamton, NY, USACHIPADD is the first to additively manufacture ultra-efficient copper cooling features directly onto the surface of GPU, CPU, and other high-power silicon chips. The company’s innovation includes materials and methods for robust bonding, manufacturing of solid and porous cooling features, enhanced materials for cooling, and manifold and precision jet design.FlexcomputeBoston, MA, USAFlexcompute builds a GPU-native physics simulation platform: Tidy3D for photonic and electromagnetic FDTD, PhotonForge for photonic design automation, Flexcompute RF for full-wave electromagnetics, and Flow360 for computational fluid dynamics and thermal analysis, delivering results 50 to 500 times faster than legacy CPU tools. FlexAgent, the company’s AI assistant, enables engineers to run and iterate simulations via natural language, accelerating chip and data center component design.HEXAspec Inc.Houston, TX, USAHEXAspec develops advanced molding compounds for semiconductor encapsulation using high-aspect-ratio hexagonal boron nitride nanosheets in polymers. Its scalable, patent-protected exfoliation process enables ten times higher thermal conductivity while maintaining electrical insulation, mechanical strength, and compatibility with standard OSAT and foundry packaging for HPC, automotive, and edge-AI applications.K1 SemiconductorChicago, IL, USAK1 Semiconductor creates engineered semiconductor wafers by peeling thin layers from high-quality single-crystal parent wafers. Its patented wafer splitting method releases a 5 to 50 micron-thick layer of single-crystal material from the parent wafer, which is then transferred and bonded to a handle wafer to create a custom semiconductor wafer.FS2Saint Louis, MO, USAFS2 is developing a monolithic 3D integration platform and memory, building next-generation stacked 3D SRAM and Process-on-Memory architectures. Its product delivers memory solutions with bandwidth, capacity, low latency, energy efficiency and cost advantages for AI workloads. Saifi Usmani is VP, Global Industry Sustainability Programs at SEMI.
Read More
For years, quantum computing has lived almost entirely in the research lab, but that is changing fast. The clearest sign of change came in spring of 2026, when IBM announced it would spin off Anderon as a standalone quantum foundry, separating its fabless chip design work from dedicated 300mm manufacturing. A company that had kept quantum fabrication tightly in house for over a decade realized that external demand now justified building a business around supplying wafers to others. When such a dominant incumbent decides to build a foundry business, that is a good indication the rest of the industry is not far behind.Over the past year, ATREG has spoken directly with a wide range of quantum hardware companies about their facility strategies. Nearly all of them are actively planning some form of scale-up, whether that means leasing cleanroom space, acquiring tools, or exploring options with existing fab operators. Alongside these conversations, we have tracked a wave of public funding rounds and cleanroom expansions from companies like QuantWare, IonQ, and IQM. Taken together, the pattern is unmistakable. Quantum computing is transitioning from a research curiosity into a manufacturing capacity question, and the companies driving this shift are bifurcating into two camps. These include vertically integrated players building or owning captive cleanrooms, and fabless designers routing wafers through commercial foundries. Both segments are now generating real fab transaction demand, which is relatively new.Why Now?Three forces are converging, with the first being government money. The U.S. Department of Commerce has signed letters of intent to invest roughly $2 billion into nine quantum computing companies in exchange for minority equity stakes. IBM’s Anderon spin-off and GlobalFoundries’ new quantum-focused business unit were granted the biggest incentives, while seven other venture-backed quantum hardware makers were granted smaller sums. Europe is moving in parallel, with France recently adding over €1 billion to its National Quantum Plan and Denmark building dedicated nanofabrication capacity for quantum chips near Copenhagen.Second, private capital is moving just as fast. Quantinuum's Nasdaq listing valued the company at over $15 billion. PsiQuantum's most recent raise pushed its valuation past $10 billion, and finally, IonQ's move to acquire SkyWater signaled that some fabless players are now willing to buy foundry capacity rather than wait for it. Third, although quantum computing is moving toward commercial production, the few specialized foundries capable of making quantum chips have already reached capacity with semiconductor demand. In discussions with foundry partners, we’ve learned that the U.S. Department of Commerce has received several proposals from companies looking for an industrialization partner and fab capacity for quantum manufacturing. Even before considering how many proposals ultimately get funded, the space available to absorb new quantum programs is limited. Separately, early company engagement is already happening well ahead of any formal facility buildout. This is a sign that demand is running ahead of infrastructure, and that latent demand is becoming active demand in real time. How Quantum Cleanroom Needs Compare to Traditional Fab Cleanroom RequirementsThe overlap with conventional semiconductor manufacturing exists, but it is narrower than the marketing suggests. Silicon-spin and superconducting modalities (the two furthest along commercially) map fairly directly onto standard 200mm-to-300mm wafer lines, running at mature nodes (16–28nm class) with no need for EUV lithography. While a qualified 200mm or 300mm metal deposition and etch line is one of the stronger brownfield fits available in the market today, quantum divergences can be seen in the following three areas. First, contamination control runs almost backwards from what logic manufacturers expect. For example, quantum fabs typically only need ISO 6 to 8 cleanroom classes. This is looser than what is standard for leading-edge logic, but specific materials like niobium, titanium nitride, and cobalt introduce isolation requirements that have nothing to do with particle counts. For instance, quantum hardware makers report that cobalt use in particular, creates friction with fabs built around conventional CMOS material rules. In addition, one major foundry noted that certain existing 300mm lines simply can't be converted for quantum work because of contamination risk from these non-standard materials.Second, packaging and assembly, not front-end fabrication, appears to be the primary roadblock. Bonding qubit chips to interposers, wiring for cryostats, and hybrid bonding require different tooling and tolerances than a front-end fab. In conversations with both foundry executives and quantum hardware companies, this stage was consistently described as the most fragmented and least mature part of the supply chain.Third, cryogenics and system integration are facilities problems, not cleanroom problems. Dilution refrigerators, cryostats, and helium supply require power capacity and vibration isolation more than particle control. In some cases, ISO 8 warehouse-grade space is sufficient. That reframes what "quantum-ready" facility space needs to look like, and it opens the door to buildings that wouldn't traditionally register as fab candidates.Where the Competitive Landscape is HeadedFewer than 100 meaningfully-funded quantum hardware companies exist today, but the small number of foundries qualified to serve them (including GlobalFoundries, imec, STMicroelectronics, Infineon, Tower, and SkyWater) are already seeing demand concentrate quickly. GlobalFoundries specifically, has emerged as an early plurality winner across multiple modalities. Whether that concentration holds, or whether scale-up costs push more players toward the SkyWater/IonQ model of outright acquisition, is one of the more consequential open questions in this space.What we are seeing in the market supports both scenarios simultaneously. Some companies are doing multi-year capacity planning well ahead of actual need, treating facility strategy as a long-lead problem to be solved early. Others are already outgrowing prototype-scale fabs and are looking to consolidate into shared or leased capacity. Both point to the same underlying reality: demand is forming faster than supply, and the packaging and assembly layer of the value chain remains particularly underserved.For a global industry built on brokering semiconductor fabrication assets, this is a familiar scenario with new variables. Brownfield capacity is a strong match for two of quantum computing's leading modalities today, with photonics and advanced packaging representing the next frontier. Ultimately, evaluating capacity gaps and moving before the rest of the market will be the next major opportunity for quantum computing's cleanroom moment. About Stephen M. RothrockStephen Rothrock is founder and CEO of ATREG, Inc. He founded ATREG in 2000 to help advanced technology companies divest and acquire infrastructure-rich manufacturing assets, including wafer fabs (front-and back-end) as well as MEMS, solar, display, and R D facilities. Over the last 25 years, ATREG has completed 40% of all global operational wafer fab sales in the semiconductor industry, representing a total of 60 transactions. Recent global acquisitions and dispositions have involved Allegro MicroSystems, Bosch, Elmos, Fujitsu, GlobalFoundries, IBM, Infineon, JDI, Maxim, Micron, Nexperia, NXP, onsemi, Plessey, Qualcomm, Renesas, Sony, Texas Instruments, TSI, VIS and more. Prior to founding ATREG, Rothrock established Colliers International’s Global Corporate Services initiative and headed the company’s U.S. division based in Seattle, Washington. Previously, he worked as director for Savills International real estate brokerage in London. There, he established the company’s corporate services platform serving large multinationals, many of whom were leading technology companies. Stephen also served on the U.K.-listed property company’s international board. He spent four years near Paris working for an international NGO. Stephen holds an MA degree in Political Theology from the University of Hull, UK and a B.A. in Business Commerce from the University of Washington in Seattle.
Read More
Daniele Pagano is a Project Manager at STMicroelectronics and standardization leader for the Heterogeneous Integration for Connectivity and Sustainability (HiCONNECTS) consortium, a coalition of 65 partners from 15 countries developing solutions for electronic components and systems. Through his work, Pagano is directly shaping the next generation of semiconductor manufacturing. SEMI spoke with Pagano about how integrating standards earlier in the development lifecycle can help bridge the gap between lab innovation and commercial deployment.SEMI: Could you tell us about your role at STMicroelectronics (ST) and what first drew you to semiconductor manufacturing?Pagano: At ST, I focus on advanced semiconductor manufacturing and innovation projects. I coordinate multidisciplinary teams, drive manufacturing development initiatives, and ensure that research outcomes translate directly into industrial applications.In parallel, I lead standardization activities focused on maintenance and cybersecurity for HiCONNECTS. These areas are central to our mission, which is to develop core technology solutions for heterogeneous integration. Through HiCONNECTS, we emphasize development in areas like RF infrastructure and IT data applications, which are quickly becoming the backbone of modern digital society. Semiconductor manufacturing attracted me because it combines science, engineering, and real-world impact. Semiconductors also underpin every technology we use today. They power everything from smartphones and electric vehicles to medical devices and industrial automation. I was also fascinated by the challenge of transforming cutting-edge research into innovations that are both highly scalable and reliable. SEMI: In HiCONNECTS, you're involved in both advanced manufacturing development and standardization. How do these two areas complement each other?Pagano: Both disciplines are closely interconnected. Advanced manufacturing focuses on creating technologies and processes that improve performance and reliability. Meanwhile, standardization helps ensure those innovations can be scaled. Without standardization, many promising technologies would struggle to move beyond the lab.Working across both areas within HiCONNECTS gives me a valuable perspective. As new technologies emerge, we can identify potential standardization needs early to ensure that available data is usable, complies with privacy and cybersecurity requirements, and can be broadly implemented across different applications. Daniele Pagano presenting at SEMICON Europa 2023SEMI: Your work explores areas like AI, digital twins, and data analytics. How do you foresee these technologies changing the way chips are produced over the coming years?Pagano: All of these technologies are becoming more crucial for the industry as semiconductor manufacturing processes get more complex. For instance, modern production environments generate large amounts of data, and AI can extract meaningful insights from that information to improve processes down the line. Digital twins are particularly valuable because they can generate virtual representations of entire production lines. They create a realistic environment for engineers to predict outcomes and improve operations without halting the entire production line. Within the HiCONNECTS project, new digital twins are being developed to optimize dispatching, scheduling, and shop floor productivity.Semiconductor factories will also become even more data-driven in the coming years, with higher levels of automation and real-time decision-making. Ultimately, digitization gives manufacturers greater freedom to produce the devices the world depends on. SEMI: Sometimes, standards are only considered after innovation. Why do you think it’s important to think about standardization throughout a research project like HiCONNECTS?Pagano: In reality, standardization should occur alongside innovation. When standards are considered at an earlier stage, researchers can better identify interoperability requirements, common terminologies, measurement methods, and best practices. However, due to the complexity of heterogeneous integration, addressing use-case requirements and standardization in tandem is key if we want to bring new technologies into production. To do this, we need cross-disciplinary collaboration. Ultimately, the goal can be broken into three steps. First, create innovative technologies in the lab. Second, ensure they can be successfully transitioned into high-volume manufacturing environments. And finally, leverage AI and digital twins to improve innovations over time. Standards play a crucial role in making all of that happen, and accomplishing each of these things is only possible when we work together. SEMI: HiCONNECTS brings together partners from industry, academia, and research organizations. What have you found most valuable about working in such a collaborative European project?Pagano: One of the greatest strengths of HiCONNECTS is our diversity of expertise. Industry partners contribute practical knowledge of manufacturing challenges and market needs, while academic and research organizations often bring fresh perspectives, novel methodologies, and deep scientific insights.Merging different disciplines also creates an environment where innovation can flourish. Challenges can be approached from multiple angles, and solutions benefit from more resources than any single organization can provide. From a personal perspective, I find the exchange of knowledge to be particularly valuable. Collaborative European projects like HiCONNECTS encourage openness, learning, and the creation of long-term professional networks. These relationships often continue beyond the life cycle of the project, and they help strengthen Europe’s semiconductor ecosystem. SEMI: Finally, what advice would you give to students and early career engineers who are considering a career in the semiconductor industry?Pagano: The first piece of advice is to embrace continuous learning. The semiconductor industry evolves rapidly, and new technologies emerge all the time. A strong foundation in engineering, physics, materials science, data science, or computer science can open several career opportunities in this field.Second, focus on developing strong technical abilities alongside effective collaboration skills. Modern semiconductor innovation relies on multidisciplinary teams, so the ability to communicate effectively and work across different domains is just as important as technical expertise.Lastly, do not underestimate the importance of resilience and problem solving. Semiconductor manufacturing is one of the most challenging engineering environments in the world, but it’s also one of the most stimulating. The technologies we develop directly impact society, so for anyone passionate about technology and innovation, it’s an exciting industry to build a career in. About HiCONNECTSHiCONNECTS (Heterogeneous Integration for Connectivity and Sustainability) is a three-year project bringing together 65 partners to develop sustainable, energy-efficient cloud and edge computing platforms. The project focuses on high-performance computing, storage infrastructure, network interfaces, and real-time analysis of IoT sensors and big data. SEMI Europe actively contributes to EU-funded initiatives, including Horizon Europe and Erasmus+ programs, capitalizing on its global member base and its role as the voice of the microelectronics industry. These activities enable SEMI to connect industry, research, and policy stakeholders while advancing European competitiveness and technological leadership. Learn more.Kartikey Srivastava is Lead of EU Projects at SEMI Europe.Daniele Pagano is Project Manager at STMicroelectronics Italy.
Read More
The SEMI Standards Team activities in Q2 focused on responding to the rapidly evolving needs of the microelectronics industry with critical revisions on key SEMI Standards. SEMI Standard F51, Guide for Elastomeric Sealing Technology, is a foundational standard for choosing and evaluating elastomeric seals. However, today’s manufacturing processes are demanding more seals with stronger chemical compatibility, lower particle and outgassing contribution, and other new and emerging considerations. SEMI is requesting industry feedback on F51 as part of its five-year review process. To participate in the next iteration of SEMI Standard F51, please complete the survey by October 15, 2026.Revisions are also underway for two important SEMI Standards. SEMI Standard E187, Specification for Cybersecurity of Fab Equipment, is currently being updated to include cybersecurity tiers based on application and need. Meanwhile, the revision to SEMI Standard E137, Guide for Final Assembly, Packaging, Transportation, Unpacking, and Relocation of Semiconductor Manufacturing Equipment, focused on an updated protocol that accounts for changes in the equipment handling environment. The revised version of E137, which included a title change, is being prepared for publication. The Korea Standards Team also hosted dedicated trainings for understanding and implementing SEMI S2, Environmental, Health, and Safety Guideline for Semiconductor Manufacturing Equipment. S2 covers the equipment used to manufacture, measure, assemble, and test semiconductor products, and it’s one of SEMI’s most widely referenced standards to date. With several new fabs coming online in 2026, SEMI Standard S2 is critical for establishing safety benchmarks ahead of tool installation. During Q2, the SEMI Water Management Group held a complimentary webinar that outlined its research findings for its two reports: Procedures Guide and Baseline and Water Savings Guide with Maturity Scale, and how the reports work with existing SEMI Standards. Some of these standards include SEMI Standard F98, Guide for Treatment of Reuse Water in Semiconductor Processing, and SEMI Standard F116, Guide for Drain Segregation for Semiconductor Manufacturing Tools to Support Site Water Reuse. The webinar can be accessed for free on demand. In addition, the SEMI Standards Team welcomed four new task forces chartered to respond to shifting industry demands. These task forces include the Flow Limiting Devices Task Force and the S2 Airborne Chemicals Task Force in North America, the Diagnostic Data Acquisition Task Force in China, and finally, the 310mm Square Panel Glass Carrier Task Force in Japan. Lastly, SEMI held 14 technical committee meetings in Q2 throughout Asia and Europe, with more than 20 standards either introduced or revised. To get involved in these SEMI Standards development efforts, become a member of the SEMI Standards Program. Membership is free. Feedback for SEMI Standard F51To adapt F51 to the modern manufacturing environment, the SEMI F51 Revision Task Force recently developed a feedback matrix outlining current priorities for this standard. For those working with elastomeric seals in any of the environments outlined on this webpage, please take a moment to provide additional input on which sealing characteristics, impurity concerns, and handling considerations should be most heavily considered in the revised version of F51. The SEMI F51 Revision Task Force is targeting a first draft by SEMICON West 2026, taking place from October 13-15. To have your feedback considered, please complete this survey by October 15, 2026. Revisions to SEMI Standards E187 and E137SEMI E187, Specification for Cybersecurity of Fab Equipment, is fundamental for outlining cybersecurity protocol for operating systems, network security, endpoint protection, and more. However, cyber threats are quickly evolving, and SEMI E187 will similarly need to be revised to address new and emerging concerns. One important revision to SEMI E187 is the introduction of three cumulative security levels (SLs), which will help equipment users and suppliers to select security profiles based on their needs. SL1 represents baseline compliance, while SL2 introduces stricter standards for equipment with greater exposure to cyber threats, like those with connections over public networks. Finally, SL3 is the most secure level of compliance, intended for applications with extremely sensitive assets to be protected. The revision of SEMI E187 represents an important step toward strengthening cybersecurity resilience across semiconductor manufacturing environments. The task force aims to advance this revision into the balloting stage this year, and continued industry participation will be essential to ensure that the final document reflects practical needs, global alignment, and broad technical consensus.Meanwhile, SEMI Standard E137, Guide for Final Assembly, Packaging, Transportation, Unpacking, and Relocation of Semiconductor Manufacturing Equipment, offers a reference for activities occurring between final assembly and moving equipment into a cleanroom. While today’s iteration covers recommended packing materials and step-by-step instructions for each subsequent process, it doesn’t account for changes in the equipment handling environment. In addition, the new version intends to be easier to understand while providing additional guidance on crating materials for specific circumstances. The revised document officially passed technical review and will be available soon. SEMI Korea S2 Safety Training From June 10-12, the SEMI Korea Standards Team hosted a SEMI Safety Standards training course. Divided into beginner and advanced sessions, the course offered a deeper understanding of safe semiconductor design and equipment evaluation. Held at the Suwon Convention Center in Suwon, Korea, it covered everything from safety standard basics all the way to in-depth explanations and practical implementation strategies for SEMI Standard S2. The June 10 program introduced the basics of SEMI Standard S2, explaining safety interlocks and emergency shutdown protocols, before diving into electrical design, fire protection, ergonomics, chemical, radiation, sound pressure, and more. For those more familiar with SEMI Safety Standards, the advanced course from June 11-12 provided more guidance on the installation of emergency stop and safety devices, chemical safety, machine safety, electrical design safety, and optimal risk assessment techniques. The advanced session went beyond SEMI Standard S2 and covered material related to SEMI Standards S6, S8, S10, S14, S17, and S28.The next SEMI Korea Standards course, SEMI Semiconductor Test Technology Training, will be held on September 9 in person at the same location. Apply today. Water Management Explanatory WebinarIn Q2, the SEMI Water Management Working Group held a webinar outlining its research for the Water Management Strategy Reports and explained how findings interact with SEMI Standards. The webinar covered procedure guidelines, water saving and baseline setting, and the solutions maturity scale. The reports were developed to help improve company water posture through recycling and reclaiming after implementing water saving strategies. They work to go beyond existing standards to help water managers understand water balance and set reasonable goals for new solutions. The reports can be downloaded here free of charge, and the webinar can be viewed on demand. New SEMI Standards Task Forces As the microelectronics industry continues to expand, four new task forces were developed in Q2 to address emerging needs. The Flow Limiting Devices Task Force was established in May 2026 to address issues identified during a reapproval ballot of SEMI S5, as well as other matters related to SEMI Standard S5 that are later identified. This task force is based and operated under the North America (NA) EH S Technical Committee Chapter. The revision to SEMI S5 was issued for ballot in Cycle 6-2026. The ballot results will be reviewed and discussed at the next task force meeting, which will be held in conjunction with SEMICON West 2026 in San Francisco, California.Also created in May, the S2 Airborne Chemicals Task Forcewill modify section 23.5 to require that the assessment criteria be demonstrated, but not necessarily during equipment evaluation. The task force leader believes that an equivalent level of safety can be achieved through alternative assessment methods. For example, industrial hygiene (IH) monitoring could be performed before opening a process chamber while personnel are wearing appropriate personal protective equipment (PPE). The results of the assessment would then determine whether PPE can be removed or should continue to be worn during subsequent work inside the chamber. This task force is based in North America and will fall under the EH S Technical Committee.Based in China, the new Diagnostic Data Acquisition Task Force will investigate problems with the implementation of Equipment Data Acquisition (EDA)/Interface A Standards in the China region and propose suggestions for improvement. This task force will also develop new SEMI Standards for EDA/Interface A and diagnostic applications as needed, in addition to promoting cooperation with other task forces in China involved with EDA/Interface A. This task force was approved in June and will fall under the China Information Control Technical Committee chapter. Finally, in response to a Line-Item Revision ballot for SEMI Standard 3D20, Specification for Panel Characteristics for Panel Level Packaging (PLP) Applications, that is being revised to include smaller panel sizes, the 310mm Square Panel Glass Carrier Task Force was formed on June 5 to revise SEMI Standard 3D23 to also include specifications for 310mm square glass carriers used in panel level packaging. Currently, 3D23 covers 510 x 515mm and 600mm x 600mm panel sizes. In its efforts to expand the standard, the task force will determine the length, width, thickness, and associated tolerances for the 310 mm panel, features like orientation corner and reference edges, backside ID mark location, and other necessary specifications. This task force is based in Japan and falls under the 3D Packaging and Integration Technical Committee. Interested in joining a task force? Apply for SEMI Standards membership.Outcomes from Q2 Technical Committee Chapter Meetings Q2 included several Technical Committee chapter meetings across Asia and Europe, where upcoming ballots and initiatives were discussed. To exchange ideas in real-time, a community page is now available on the Connect@SEMI platform. Japan Meetings The Automation Technology Japan Technical Committee met on June 19 and presented reports from the AI, Surface Mount Technology, and F-GEM task forces. The Information Control Japan Technical Committee convened on June 17 and approved SNARF 7476 , Guide for Maintenance Robot Communication.The 3D Packaging Integration Japan Technical Committee conducted ballot reviews on June 5 for a line-item revision to SEMI Standard G82-1115, Specification for 300 mm Load Port for Frame Cassettes in Backend Process, as well as a line-item revision to SEMI G95-1120, Specification for Mechanical Features of 450 mm Load Port for Tape Frame Cassettes in the Backend Process. The EHS Japan Technical Committee met on June 3 to present several task force reports, including one from the Global Seismic Protection Task Force, another from the Mobile Maintenance Robot Safety Task Force, and several more from various SEMI Standard revision Task Forces. The Gases and Facilities Japan Joint Technical Committee reviewed the revision ballot for SEMI Standard E137-0705 on May 29. The committee approved the revision and a title change. Once published, the Standard will be called Guide for Final Assembly, Packing, Transportation, Unpacking, and Moving of Semiconductor Manufacturing Equipment. The Physical Interface Carriers Japan Technical Committee proposed a new primary standard, Specification for Enhanced Handoff Interface, and a complementary subordinate standard, Specification for Modbus Communication for Enhanced Handoff Interface, on May 21. These documents passed review and are currently being processed for publication.The Liquid Chemicals Japan Technical Committee met on May 21 to present several task force reports, including Liquid Filter Task Force, Liquid-Borne Particle Counter Task Force, and Valve Fitting Task Force. Ballot 7267A, Revision to SEMI C77-0818 with title change to: Test Method for Determining the Counting Efficiency of Liquid-Borne Particle Counters for Which the Minimum Detectable Particle Size is in the Range of 20 nm and 100 nm, was authorized in Cycle 8-2026, which will be issued in late September.The Information Control Japan Technical Committee met on April 17 to report the Ratification Ballot results for Line-Item Revision to SEMI E170-0520, Specification for Secured Foundation of Recipe Management System (SFORMS) and SEMI E170.1-0520, Specification for SECS-II Protocol for Secured Foundation of Recipe Management System. This ballot passed, and both primary and subordinate standards will be available soon. The Silicon Wafer Japan Technical Committee convened on April 17 to review ballot 6570D for a new SEMI Standard, Guide for Measuring Bulk Micro Defect Density and Denuded Zone Width in Annealed Silicon Wafers by a Laser Scattering Tomography Technique. This document passed review and is currently being processed for publication.Korea MeetingsThe EHS Korea Technical Committee also met on June 19 to discuss its Field-Based Safety Subcommittee, Regulatory Alignment Subcommittee, Robot Safety Task Force, and S2 Major Revision Liaison Task Force.The Information Control Korea Technical Committee reviewed reports from the GEM300 Task Force, the Diagnostic Data Acquisition Task Force, and the Advanced Back-End Factory Task Force, on April 23.China MeetingThe Information Control China Technical Committee met on June 2 and approved SNARF 7475, Line Item Revision to E90-1224, Specification for Substrate Tracking and E90.1-1224, Specification for SECS-II Protocol Substrate Tracking. The goal is to help both equipment manufacturers and factories using E90 achieve precise and consistent information exchange regarding substrate state.Taiwan MeetingThe FPD Metrology Taiwan Technical Committee discussed and adjudicated ballot 7352, Revision to SEMI D056-0519, Test Method for Measurement for Ambient Contrast of Flat Panel Displays, which failed technical review, on May 22. The updated ballot 7352A is issued in Cycle 7-26 and is scheduled for review on November 20, 2026.Europe MeetingThe Compound Semiconductor Materials Europe Technical Committee met on April 14. Ballot 7111, Revision of SEMI M81-0418, Guide for Defects Found in Monocrystalline Silicon Carbide Substrates, passed technical review. The revised SEMI M81 standard is being processed for publication and will be available for purchase online.In Case You Missed It – Standards Suite Overview White Paper The SEMI Standards team released a complimentary, 23-page white paper, titled Selecting the Right Standards for Your Factory Use Case and Technology Needs. This paper covers four SEMI Standards Suites to support equipment communications and automation. It breaks possibilities into smaller groups of existing standards to help factories and suppliers scale more efficiently. Download the white paper. New and Revised Standards Released in Q2 April 2026May 2026June 2026Get InvolvedSEMI Standards development activities take place throughout the year in all major manufacturing regions. To participate, join the SEMI International Standards Program.SEMI Standards are available through individual download purchases or online via SEMIViews. Watch this video to learn more about how SEMIViews offers a cost-effective and streamlined way to access 1,110+ SEMI Standards. Sign up for a 30-day SEMIViews trial.For more information, please visit the Standards website and events page. For any questions regarding SEMI Standards activities, please contact your local SEMI Standards staff.Paul Trio is Director of Standards at SEMI.
Read More
Several years ago, the ESD Alliance, a SEMI Technology Coalition contacted Jay Vleeschhouwer, Managing Director of Software Research at Griffin Securities, about his yearly presentation on the state of EDA and the industry’s successes during the Design Automation Conference (DAC). He willingly agreed, and it has been a yearly tradition for our executives to interview Vleeschhouwer.This year is no exception. He took time to chat with us about this year’s presentation and his findings that show EDA’s phenomenal revenue growth and startup activity. Our talk covered EDA mergers and acquisitions, AI and what’s next.In his presentation, Vleeschhouwer references the ESD Alliance quarterly Electronic Design Market Data (EDMD) report on EDA, Semiconductor IP and Services industry revenue data from public and private companies. Rogers: EDA has grown continuously since 2010. What do you attribute the growth to? The revenue numbers suggest it's sustainable.Vleeschhouwer: The growth can be attributed to many of the factors that have been in place for many years now. What we have observed from the ESDA (EDMD) market data, for example, is that numerous categories, which we include in our quarterly report, have been growing continuously on a trailing 12-month basis for many years. There are far more categories that are growing than are not growing. In fact, very few categories show no growth or little growth.The growth has been diverse across the categories, a crucial underpinning for growth in the industry. It is also different from the situation a quarter century ago or more. I often make this point to investors when speaking about EDA. Years ago, the growth would typically be much more limited in terms of the product categories that perhaps one or two categories would be showing good growth or well above industry average growth. Those would eventually run their course.Now, what we've seen is multiple categories growing, in some cases, well above the industry average. That is driven by technology needs on the part of the customers. In other words, when you think about how the whole design and engineering process has evolved, requiring more product categories to be integrated, to be used heuristically, then that underpins the improved and more diverse growth across the industry that we've seen now for many years.It also ties into what’s gone on with the two largest vendors, Cadence and Synopsys. This ties directly to why their market share has gone from just over half of industry revenue now to nearly three-quarters of industry revenue. Their portfolios have become increasingly diverse and more integrated. A lot of that was inorganic through acquisition, but mostly in the last number of years through internal development. These growth phenomena and market share phenomena are highly correlated.Rogers: How is AI impacting industry growth in the EDA companies themselves? Should we expect a flurry of mergers and acquisitions?Vleeschhouwer: The first of those two questions is an important one. Unfortunately, we don't have a great answer yet. We've been encouraging the largest vendors to be more explicit to the extent they can be about the AI impact on their business. Cadence and Synopsys have separately branded AI products or agents. Cadence has a family of products. Synopsys has its family of products. Those are separately priced.We would love to see over time how those are contributing to revenue. At the same time, or over time, we do expect not only EDA, but for all our Engineering Software companies, AI will become increasingly infused in legacy products. It's just going to become part of the capabilities naturally offered to customers. We’re going to see hybrid portfolios that we have today separately branded as additional flavors, and those capabilities will be increasingly embedded as well.As that occurs, it would naturally become more difficult to separately attribute revenues to AI, but to the extent that there are separate brands, then it should be possible for the companies to be more explicit about those contributions. Synopsys will be hosting an investor day in New York at the end of September. I'm sure this question will come up as to the contribution of AI, among many other questions. At this point, all I can say is our observation is that, of the three major categories that we define as Engineering Software—EDA, Technical Software, and architecture, engineering, and construction (AEC)—it appears AI availability, customer adoption and production is further along in EDA.That observation is based on customers’ commentary and presentations at, for example, the Cadence conference and the Synopsys conference. It's that accumulated customer presentation and availability of customer results that suggests that AI adoption is further along in that part of Engineering Software, and the rest will undoubtedly follow over time. On the Technical Software side or industrial side of Engineering Software, the AEC side, I have no doubt it will become increasingly important. So far, however, for some good technical reasons, we think AI adoption is further along in EDA.Cohen: You mention the EDMD report on industry revenue in your DAC presentation. The numbers reported are not the same as the numbers you tend to report in your publications. Can you discuss the differences?Vleeschhouwer: Yes, thank you for the easy question. I was waiting for that one. As you know, we've been using this data for over a quarter of a century, every quarter. I always make the distinction in the report that the difference between what the SEMI/ESD Alliance report shows and what my report shows is a single category, and that is non-reporting-company IP.We include reporting-company IP, but for the purpose of our parsing of the data, we exclude from the total and from the growth comparisons what the market data refers to as the non-reporting-company IP. In all other respects, the categories line up. As much as possible, we try to correlate the industry data by geo and by category to the company results for market share calculation purposes, for growth purposes, and the like. Rogers: What should SEMI readers be looking for in terms of 2027 EDA revenue?Vleeschhouwer: All I can do is repeat what we've published in our industry report, which is that we expect industry growth to exceed $17 billion this year. That's based on our estimates for Cadence's revenues, what we call Synopsys Classic, plus an assumption for the EDA part of Ansys, and only the EDA part of Ansys, plus some assumption for Siemens EDA. Siemens EDA has done well since Mentor was acquired over nine years ago. That business has doubled since Mentor's last year as a public company. That includes some small acquisitions that Siemens has since done, but again, the overall business has roughly doubled.The business, I should also point out, on a quarterly and even annual basis, can be quite variable at Siemens because of the nature of their revenue models. Taking that into account, again, we expect over $17 billion this year in industry revenue, as compared with nearly $16 billion in 2025. This should be another good year for EDA. With respect to 2027, we haven't yet published an industry forecast. I have no doubt it will continue to grow, but we have only published forecasts for Cadence and Synopsys individually. Even though they still account for almost three-fourths of the industry, we would have to give a number for the other, more than one-fourth of the industry, which at this point we've not yet published.About Jay Vleeschhouwer  Jay Vleeschhouwer, Managing Director of Software Research at Griffin Securities, has more than 40 years of research analyst experience in the technology sector, including software, semiconductors and computer hardware. Julie Rogers is executive director of the ESD Alliance.  Paul Cohen is Senior Manager of the ESD Alliance.
Read More
The counterfeit semiconductor market is estimated to be multi‑billion‑dollar in scale. OBSIDIA's own customer interviews put the true toll above $100 billion a year, touching everything from foundries losing 5%+ of revenue to counterfeits to failures downstream that cost reputation, business, or lives.As semiconductor devices become increasingly central to artificial intelligence, critical infrastructure, automotive systems, and national security applications, trust in the underlying hardware is emerging as a strategic concern. While the industry has made significant progress in tracking materials, documenting supply chains, and improving cybersecurity, questions remain around authenticity, provenance, and whether organizations can truly trust the devices powering modern technology.To explore these challenges, SEMI’s Mayura Padmanabhan and Nishita Rao spoke with Erik Hosler, Founder and CEO of OBSIDIA Semiconductors Inc, about counterfeit electronics, traceability, trusted hardware, AI infrastructure, and the role industry collaboration can play in securing the semiconductor ecosystem.For readers who may not be familiar with OBSIDIA, what challenge is the company trying to solve?Hosler describes OBSIDIA's mission through a comparison that many technology professionals immediately understand."OBSIDIA is focused on delivering security at the hardware level for the semiconductor industry. A great way to think about that is the analog of antivirus in software." While software has long benefited from tools that help validate and protect systems, he believes the semiconductor industry has lacked an equivalent capability at scale for hardware."Nothing really exists in the semiconductor ecosystem on a large scale for hardware security. The ability to really trust that the semiconductor devices that we rely on every day are authentic and conforming." That gap is what OBSIDIA aims to address. By examining the physical characteristics of devices, the company seeks to verify authenticity at multiple points throughout the semiconductor lifecycle."Through our technology, we're able to authenticate the integrity and quality of devices at any level of integration within the semiconductor supply chain, from the wafer level all the way up to and including the application." This capability was demonstrated as part of a DARPA Small Business Innovation Research (SBIR) Phase II award OBSIDIA completed a few years ago as well as projects with MITRE and Kostas Research Institute for Homeland Security.Why has semiconductor authenticity become such an important issue today?According to Hosler, semiconductor authenticity is no longer a niche concern. As the world becomes increasingly dependent on electronics, the potential impact of counterfeit and non-conforming devices continues to grow."There have been a lot of studies over the past couple of years analyzing how many of these types of devices are actually in our ecosystem. Even at the highest level of scrutiny within the Department of Defense in the U.S., anywhere from 10 to 15 percent of their electronics contain counterfeit devices. That's a very scary statistic."The issue extends beyond critical systems and into everyday life."The chance that you have a counterfeit device in one of your electronics within arm's reach at any point in time during the day is very real." Interestingly, Hosler does not characterize counterfeiting primarily as sophisticated malicious activity."It's not a targeted event. It's a crime of opportunity." He pointed to supply chain disruptions as examples of how legitimate shortages can create openings for non-conforming devices to enter the market."Counterfeits aren't just something bought off the back of a truck. They're sprinkled into our ecosystem and appear seemingly at random." SEMI's Traceability Phase Zero discussions highlighted industry concerns around provenance, authenticity, lifecycle visibility, and supply chain assurance. From your perspective, what are the biggest traceability challenges facing the semiconductor industry today?When discussing traceability, Hosler pointed to a challenge that extends beyond tracking high-value chips themselves."Let's say we have a $30,000 NVIDIA GPU. Tracking that through the supply chain is dollar-for-dollar kind of equivalent to tracking a car through the supply chain. You're going to want to make sure you know where that asset is at any point in time."The challenge begins after that component becomes part of a larger system."Where this paradigm breaks is at integration." Modern electronics consist of hundreds of interconnected components. Even when a high-performance processor has been carefully tracked and validated, a much smaller supporting component can introduce unexpected risk."If one of those five-cent devices on that PCB is counterfeit, it compromises the entire performance of that board, and by extension, that $30,000 GPU." That observation became one of the defining themes of our conversation:“A $30,000 GPU can be compromised by a five-cent component.” For Hosler, true traceability cannot stop at flagship devices. It must extend across entire assemblies and systems.OBSIDIA was recently named among the seven companies signing U.S. CHIPS and Science Act letters of intent for compute supply chain R D. What does this recognition say about the growing importance of hardware trust and security within the semiconductor ecosystem?Hosler views the recognition as evidence that the industry is paying increasing attention to the importance of trusted hardware."What the CHIPS R D money allows us to do is accelerate the commercialization of the technology."He noted that OBSIDIA has already moved beyond the lab and into commercial deployment."We already have a system deployed at a commercial site today. We are in the field running our machine, collecting data with our customer, providing feedback to their customers and suppliers about what's happening in the ecosystem." The funding, he explained, helps accelerate the journey from research to industry adoption while enabling the company to scale its technology across a growing number of use cases.Hosler also contrasted OBSIDIA's approach with current industry practices."If you receive a thousand devices, you typically send three of those devices out for validation at a third-party lab. Then you have to assume the other 997 were authentic."OBSIDIA's vision is to move beyond sampling."What OBSIDIA allows you to do is measure every single device that you receive." By reducing dependence on sample-based validation, organizations gain the opportunity to improve confidence in every component entering their manufacturing process. Many companies already have authentication, tracking, or security technologies. What is still missing to achieve true end-to-end traceability across the semiconductor lifecycle?A recurring theme during industry traceability discussions is the tension between sharing information and protecting intellectual property.Hosler acknowledged that companies are understandably protective of their manufacturing knowledge, process data, and design information."There is a strong desire to control IP, control process data, and control yield data." Rather than attempting to change that reality, OBSIDIA designed its technology around it."So OBSIDIA really looked at its technology and asked how we can be IP and data agnostic." That philosophy led to one of the most memorable statements from the interview:“We're the company that knows nothing.”Hosler explained that customers can maintain existing workflows, processes, and controls without exposing sensitive data."You can maintain whatever structures and regulations and procedures you have already and we will be an addition to that without any need to know anything about what you are doing."By focusing on spectroscopic measurements rather than imaging or design extraction, the company seeks to strengthen trust without requiring access to proprietary information. As AI systems become increasingly important in commercial and national security applications, how does trust in the underlying hardware affect trust in AI itself?Artificial intelligence emerged repeatedly throughout the discussion, particularly as organizations invest heavily in AI infrastructure and advanced computing systems."The AI infrastructure buildout is one of the greatest projects within the U.S. from a manufacturing perspective that has happened in decades." Hosler sees this expansion as both an opportunity and a responsibility for the semiconductor industry."AI is going to be active in the systems that we directly engage with on a daily basis, whether that's the plane you're flying on, or the car you're driving." As AI becomes integrated into transportation, industrial automation, critical infrastructure, and consumer applications, trust in the underlying hardware becomes increasingly important.Drawing a comparison to the evolution of cybersecurity, Hosler believes the industry is approaching an important moment."We don't want to end up with a major incident that we all look back on as a major misstep by us in the industry, just like we saw with cybersecurity." "We are poised for a similar incident when it comes to hardware security." Where do you see the greatest opportunities for progress in the next three years, and how can SEMI help support that progress?Despite the challenges, Hosler remains optimistic about the industry's direction."I think where we are seeing the most progress is the recognition of the problem." He pointed to increasing attention from government, industry, and technology providers as evidence that momentum is building around hardware trust and infrastructure assurance."This is a major opportunity for the industry to rally around that call and deliver a solution that not only covers AI space but covers the rest of our infrastructure as well." Hosler also sees a critical role for standards organizations."SEMI is the perfect place, given that all the partners are already there, all the end customers, all the interested parties." Reflecting on SEMI's Traceability Phase Zero effort, he described it as an important starting point that helped identify both challenges and opportunities."The Phase Zero study was a great first step to realize what the challenges are and what the potential opportunities are. Now a Phase One is required to consolidate the feedback and align on a solution." One trend worth watching going forward: the industry's accelerating shift toward chiplets and multi-vendor advanced packaging means a single finished package can now contain die from several different suppliers, assembled by a third party - a structural change to the supply chain that raises new provenance questions of its own.Closing ThoughtsAt the conclusion of our discussion, Hosler offered a simple piece of advice for organizations focused on quality, trust, and supply chain security:“Be skeptical.” He encouraged leaders to look beyond documentation and assumptions and spend more time understanding what is happening on the factory floor."Even though everything looks okay on the outside, what's happening on the factory floor could be a very different story.""Don't assume everything is okay. Dig that next layer deeper." As semiconductor supply chains become increasingly complex and AI systems become more deeply embedded in everyday life, trust can no longer be viewed solely as a matter of paperwork, compliance, or process. As Hosler emphasized throughout our conversation, building confidence in modern technology ultimately begins with confidence in the hardware itself. About Erik HoslerErik Hosler is Founder of OBSIDIA Semiconductors, a company focused on semiconductor authenticity, hardware trust, and supply chain security through advanced RF-based device verification technologies. OBSIDIA's mission is to enable scalable, non-destructive verification of semiconductor devices across the electronics lifecycle Mayura Padmanabhan is a Technical Project Manager at SEMI, focused on advancing semiconductor cybersecurity, traceability, and supply chain resilience through industry standards and collaborative initiatives. Nishita Rao is Director of Product Marketing at SEMI, leading global marketing initiatives that drive industry engagement, thought leadership, and awareness across the semiconductor value chain.
Read More