
Several years ago, the ESD Alliance, a SEMI Technology Coalition contacted Jay Vleeschhouwer, Managing Director of Software Research at Griffin Securities, about his yearly presentation on the state of EDA and the industry’s successes during the Design Automation Conference (DAC). He willingly agreed, and it has been a yearly tradition for our executives to interview Vleeschhouwer.
This year is no exception. He took time to chat with us about this year’s presentation and his findings that show EDA’s phenomenal revenue growth and startup activity. Our talk covered EDA mergers and acquisitions, AI and what’s next.
In his presentation, Vleeschhouwer references the ESD Alliance quarterly Electronic Design Market Data (EDMD) report on EDA, Semiconductor IP and Services industry revenue data from public and private companies.
Rogers: EDA has grown continuously since 2010. What do you attribute the growth to? The revenue numbers suggest it's sustainable.
Vleeschhouwer: The growth can be attributed to many of the factors that have been in place for many years now. What we have observed from the ESDA (EDMD) market data, for example, is that numerous categories, which we include in our quarterly report, have been growing continuously on a trailing 12-month basis for many years. There are far more categories that are growing than are not growing. In fact, very few categories show no growth or little growth.
The growth has been diverse across the categories, a crucial underpinning for growth in the industry. It is also different from the situation a quarter century ago or more. I often make this point to investors when speaking about EDA. Years ago, the growth would typically be much more limited in terms of the product categories that perhaps one or two categories would be showing good growth or well above industry average growth. Those would eventually run their course.
Now, what we've seen is multiple categories growing, in some cases, well above the industry average. That is driven by technology needs on the part of the customers. In other words, when you think about how the whole design and engineering process has evolved, requiring more product categories to be integrated, to be used heuristically, then that underpins the improved and more diverse growth across the industry that we've seen now for many years.
It also ties into what’s gone on with the two largest vendors, Cadence and Synopsys. This ties directly to why their market share has gone from just over half of industry revenue now to nearly three-quarters of industry revenue. Their portfolios have become increasingly diverse and more integrated. A lot of that was inorganic through acquisition, but mostly in the last number of years through internal development. These growth phenomena and market share phenomena are highly correlated.
Rogers: How is AI impacting industry growth in the EDA companies themselves? Should we expect a flurry of mergers and acquisitions?
Vleeschhouwer: The first of those two questions is an important one. Unfortunately, we don't have a great answer yet. We've been encouraging the largest vendors to be more explicit to the extent they can be about the AI impact on their business. Cadence and Synopsys have separately branded AI products or agents. Cadence has a family of products. Synopsys has its family of products. Those are separately priced.
We would love to see over time how those are contributing to revenue.
At the same time, or over time, we do expect not only EDA, but for all our Engineering Software companies, AI will become increasingly infused in legacy products. It's just going to become part of the capabilities naturally offered to customers. We’re going to see hybrid portfolios that we have today separately branded as additional flavors, and those capabilities will be increasingly embedded as well.
As that occurs, it would naturally become more difficult to separately attribute revenues to AI, but to the extent that there are separate brands, then it should be possible for the companies to be more explicit about those contributions.
Synopsys will be hosting an investor day in New York at the end of September. I'm sure this question will come up as to the contribution of AI, among many other questions. At this point, all I can say is our observation is that, of the three major categories that we define as Engineering Software—EDA, Technical Software, and architecture, engineering, and construction (AEC)—it appears AI availability, customer adoption and production is further along in EDA.
That observation is based on customers’ commentary and presentations at, for example, the Cadence conference and the Synopsys conference. It's that accumulated customer presentation and availability of customer results that suggests that AI adoption is further along in that part of Engineering Software, and the rest will undoubtedly follow over time.
On the Technical Software side or industrial side of Engineering Software, the AEC side, I have no doubt it will become increasingly important. So far, however, for some good technical reasons, we think AI adoption is further along in EDA.
Cohen: You mention the EDMD report on industry revenue in your DAC presentation. The numbers reported are not the same as the numbers you tend to report in your publications. Can you discuss the differences?
Vleeschhouwer: Yes, thank you for the easy question. I was waiting for that one. As you know, we've been using this data for over a quarter of a century, every quarter. I always make the distinction in the report that the difference between what the SEMI/ESD Alliance report shows and what my report shows is a single category, and that is non-reporting-company IP.
We include reporting-company IP, but for the purpose of our parsing of the data, we exclude from the total and from the growth comparisons what the market data refers to as the non-reporting-company IP. In all other respects, the categories line up. As much as possible, we try to correlate the industry data by geo and by category to the company results for market share calculation purposes, for growth purposes, and the like.
Rogers: What should SEMI readers be looking for in terms of 2027 EDA revenue?
Vleeschhouwer: All I can do is repeat what we've published in our industry report, which is that we expect industry growth to exceed $17 billion this year. That's based on our estimates for Cadence's revenues, what we call Synopsys Classic, plus an assumption for the EDA part of Ansys, and only the EDA part of Ansys, plus some assumption for Siemens EDA. Siemens EDA has done well since Mentor was acquired over nine years ago. That business has doubled since Mentor's last year as a public company. That includes some small acquisitions that Siemens has since done, but again, the overall business has roughly doubled.
The business, I should also point out, on a quarterly and even annual basis, can be quite variable at Siemens because of the nature of their revenue models. Taking that into account, again, we expect over $17 billion this year in industry revenue, as compared with nearly $16 billion in 2025. This should be another good year for EDA.
With respect to 2027, we haven't yet published an industry forecast. I have no doubt it will continue to grow, but we have only published forecasts for Cadence and Synopsys individually. Even though they still account for almost three-fourths of the industry, we would have to give a number for the other, more than one-fourth of the industry, which at this point we've not yet published.
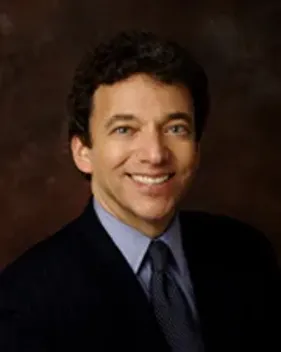 About Jay Vleeschhouwer
Jay Vleeschhouwer, Managing Director of Software Research at Griffin Securities, has more than 40 years of research analyst experience in the technology sector, including software, semiconductors and computer hardware.
Julie Rogers is executive director of the ESD Alliance.
Paul Cohen is Senior Manager of the ESD Alliance.


