downloadGroupGroupnoun_press release_995423_000000 copyGroupnoun_Feed_96767_000000Group 19noun_pictures_1817522_000000Member company iconResource item iconStore item iconGroup 19Group 19noun_Photo_2085192_000000 Copynoun_presentation_2096081_000000Group 19Group Copy 7noun_webinar_692730_000000Path
Skip to main content
Default Banner Image

SEMI Press Release

ID
semi-press-release

MILPITAS, Calif. — January 14, 2025 — Electronic System Design (ESD) industry revenue increased 8.8% to $5,114.5 million in the third quarter of 2024 from the $4,702.4 million registered in the third quarter of 2023, the ESD Alliance, a SEMI Technology Community, announced today in its latest Electronic Design Market Data (EDMD) report. The four-quarter moving average, which compares the most recent four quarters to the prior four, rose 13.7%.   

SEMI & ESDA“The electronic design automation (EDA) industry reported significant revenue growth in Q3 2024,” said Walden C. Rhines, Executive Sponsor of the SEMI Electronic Design Market Data report. “Product categories Computer-Aided Engineering and Services posted double-digit growth, with Printed Circuit Board and Multi-Chip Module, and Semiconductor Intellectual Property also posting growth. Regionally, the Americas along with Europe, Middle East, and Africa reported double digit growth. The four-quarter moving average increased for all product categories and regions.”

The companies tracked in the EDMD report employed 62,417 people globally in Q3 2024, a 4.5% increase over the Q3 2023 headcount of 59,737, but down 1.2% compared to Q2 2024. 

The quarterly EDMD report contains detailed revenue information within the following category and geographic breakdowns. 

Revenue by Product and Application Category – Q3 2024 Year-Over-Year Change

  • Computer-Aided Engineering (CAE) revenue jumped 16% to $1,922.2 million in Q3 2024. The four-quarter CAE moving average increased 14.5%. 
  • Integrated Circuit (IC) Physical Design and Verification revenue decreased 5.5% to $854.4 million. The four-quarter moving average for the category increased 4.3%. 
  • Printed Circuit Board (PCB) and Multi-Chip Module (MCM) revenue rose 5.8% to $450.8 million. The four-quarter moving average for PCB and MCM rose 9.1%.
  • Semiconductor Intellectual Property (SIP) revenue increased 7% to $1,686.2 million. The four-quarter SIP moving average rose 17.5%.
  • Services revenue rose 45.2% to $200.8 million. The four-quarter Services moving average rose 30.8%.

Revenue by Region – Q3 2024 Year-Over-Year Change

  • The Americas, the largest reporting region by revenue, procured $2,325.4 million of electronic system design products and services in Q3 2024, a 17.2% increase. The four-quarter moving average for the Americas rose 17%. 
  • Europe, Middle East, and Africa (EMEA) procured $645.6 million of electronic system design products and services, a 17.1% increase. The four-quarter moving average for EMEA grew 15.4%. 
  • Japan’s procurement of electronic system design products and services decreased 3.5% to $298.5 million. The four-quarter moving average for Japan increased 7.6%. 
  • Asia Pacific (APAC) procured $1,845 million of electronic system design products and services, an 0.7% decrease. The four-quarter moving average for APAC grew 10.6%.  

About the EDMD Report

The ESD Alliance Electronic Design Market Data report presents Electronic Design Automation (EDA), SIP and Services industry revenue data quarterly. Both public and private companies contribute data to the report available from SEMI. Each quarterly report is published approximately three months after quarter close. EDMD report data is segmented as follows: 

  • Revenue by product category (CAE, IC Physical Design and Verification, SIP, PCB/MCM Layout, and Services) including numerous detailed sub-categories
  • Revenue by geographic region (Americas, EMEA, Japan and APAC)
  • Total employment at participating companies

For information about SEMI market research reports, visit the SEMI Market Research Reports and Databases Catalog.

About the Electronic System Design Alliance

The ESD Alliance, a SEMI Technology Community, offers initiatives and activities that bring value to our entire industry including:

  • Coordinating and amplifying the collective and regional voices of the industry.
  • Continually promoting the value the industry delivers to the global semiconductor and electronics industry.
  • Addressing and defending threats and reducing risks to the industry.
  • Achieving efficiencies for the industry.
  • Marketing the attractiveness of the design ecosystem as an ideal industry for pursuing a career.
  • Enabling networking, sharing and collaboration across the industry.

Contact Paul Cohen at [email protected] or Bob Smith at [email protected] for more details.

Engage with the ESD Alliance

www.esd-alliance.org

ESD Alliance Bridging the Frontier blog

X: @ESDAlliance

LinkedIn

Facebook

About SEMI

SEMI® is the global industry association connecting over 3,000 member companies and 1.5 million professionals worldwide across the semiconductor and electronics design and manufacturing supply chain. We accelerate member collaboration on solutions to top industry challenges through Advocacy, Workforce Development, Sustainability, Supply Chain Management and other programs. Our SEMICON® expositions and events, technology communities, standards and market intelligence help advance our members’ business growth and innovations in design, devices, equipment, materials, services and software, enabling smarter, faster, more secure electronics. Visit www.semi.org, contact a regional office, and connect with SEMI on LinkedIn and X to learn more.

The information supplied by the ESD Alliance is believed to be accurate and reliable, but the ESD Alliance assumes no responsibility for any errors that may appear in this document. All trademarks and registered trademarks are the property of their respective owners.

Association Contacts                                                                    

Paul Cohen
Phone: 508-769-2106 
Email: [email protected]

Jack Taylor
Phone: 512-560-7143 
Email: [email protected]
MILPITAS, Calif. — January 7, 2025 — The semiconductor industry is expected to start 18 new fab construction projects in 2025*, according to SEMI's latest quarterly World Fab Forecast report. The new projects include three 200mm and fifteen 300mm facilities, the majority of which are expected to begin operations from 2026 to 2027. 

SEMIIn 2025, the Americas and Japan are the leading regions with four projects each. The China and Europe & Middle East regions are each tied for third place with three planned construction projects. Taiwan has two planned projects, while Korea and Southeast Asia have one project each for 2025.
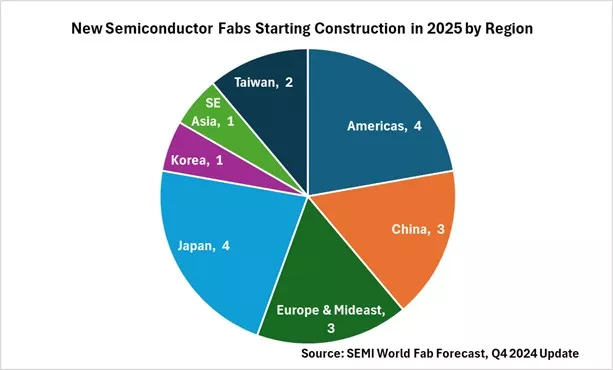
 

New semiconductor fabs starting construction


“The semiconductor industry has reached a pivotal juncture, with investments driving both leading-edge and mainstream technologies to meet evolving global demands,” said Ajit Manocha, SEMI President and CEO. “Generative AI and high-performance computing are fueling advancements in the leading-edge logic and memory segments, while mainstream nodes continue to underpin critical applications in automotive, IoT and power electronics. The construction of 18 new semiconductor fabs set to begin in 2025 demonstrates the industry’s commitment to support innovation and significant economic growth.”

Covering 2023 to 2025, the 4Q 2024 edition of World Fab Forecast report shows that the global semiconductor industry plans to begin operation of 97 new high-volume fabs. This includes 48 projects in 2024 and 32 projects set to launch in 2025, with wafer sizes ranging from 300mm to 50mm.

Advanced Nodes Lead Semiconductor Industry Expansion 

Semiconductor capacity is projected to further accelerate, with a 6.6% yearly growth rate forecast to total 33.6 million wafers per month (wpm)** for 2025. This expansion will be primarily driven by leading-edge logic technologies in high-performance computing (HPC) applications and the increasing penetration of generative AI in edge devices.

The semiconductor industry is intensifying efforts to build advanced computing capabilities, responding to the escalating computational demands of large language models (LLMs). Chip manufacturers are aggressively expanding advanced node capacities (7nm and below), which are expected to see an industry-leading 16% yearly growth rate for an increase of more than 300,000 wpm to total 2.2 million wpm in 2025.

Boosted by China’s chip self-sufficiency strategy and expected demand from automotive and IoT applications, mainstream nodes (8nm~45nm) are predicted to add another 6% capacity, surpassing the 15 million wpm milestone in 2025.

Mature technology nodes (50nm and above) are experiencing a more conservative expansion, reflecting the market’s slow recovery and low utilization rates. This segment is expected to grow 5%, reaching 14 million wpm in 2025.

Foundry Segment Continues Strong Capacity Growth 

Foundry suppliers are expected to remain the leaders in semiconductor equipment purchases. The Foundry segment is projected to increase capacity by 10.9% year-over-year, rising from 11.3 million wpm in 2024 to a record 12.6 million wpm in 2025.

The overall memory segment shows a measured capacity expansion, with modest growth of 3.5% in 2024 and 2.9% in 2025. However, strong generative AI demand is driving significant changes in memory markets. High-bandwidth memory (HBM) is experiencing a notable surge, creating divergent capacity growth trends between the DRAM and NAND flash segments.

The DRAM segment is expected to maintain robust growth, projecting approximately a 7% year-over-year increase to 4.5 million wpm in 2025. Conversely, the installed capacity for 3D NAND is anticipated to grow 5%, reaching 3.7 million wpm in the same period.

The latest update of the SEMI World Fab Forecast report, published in December 2024, lists more than 1,500 facilities and lines globally, including 180 volume facilities and lines with various probabilities expected to start operation in 2025 or later.  

Download a sample of the SEMI World Fab Forecast report.

For details about SEMI reports on other semiconductor sectors, visit SEMI Market Intelligence or contact us at [email protected].

*The fab count does not include research and development (R&D) lines

**200mm equivalent

About SEMI

SEMI® is the global industry association connecting over 3,000 member companies and 1.5 million professionals worldwide across the semiconductor and electronics design and manufacturing supply chain. We accelerate member collaboration on solutions to top industry challenges through Advocacy, Workforce Development, Sustainability, Supply Chain Management and other programs. Our SEMICON® expositions and events, technology communities, standards and market intelligence help advance our members’ business growth and innovations in design, devices, equipment, materials, services and software, enabling smarter, faster, more secure electronics. Visit www.semi.org, contact a regional office, and connect with SEMI on LinkedIn and X to learn more.  

Association Contacts

Samer Bahou/SEMI Corporate
Phone: 1.408.943.7870
Email: [email protected] 

Christian G. Dieseldorff/SEMI US
Phone: 1.408.943.7940
Email: [email protected]  

Chih-Wen Liu/SEMI Taiwan
Phone: 886.3.560.1777
Email: [email protected]

SEOUL, South Korea ─ December 17, 2024 ─ SEMICON Korea 2025 will take place Feb. 19-21 in Seoul at the COEX offering a comprehensive look into AI-driven technological advancements and edge technologies poised to shape the future of the global semiconductor industry. Themed Lead the Edge, the event will feature key topics such as cutting-edge chip manufacturing technology trends, sustainability, smart manufacturing, regional semiconductor investment programs, workforce development, and international research and development (R&D) collaboration seminars. Registration is now open.

SEMICON KOREASEMICON Korea will host keynote presentations from industry leaders including AMD, Applied Materials, imec, Samsung and Synopsys. More than 200 global experts and scholars in the semiconductor field will share their insights across 30+ conferences. The exhibition will showcase over 2,300 booths featuring cutting-edge semiconductor manufacturing technologies and services from over 500 domestic and international companies.

SEMICON Korea 2025 Highlights

  • STS (SEMI Technology Symposium) – This symposium will highlight the latest technology advances and roadmaps focused on six key semiconductor manufacturing processes: 
    • CMP & Cleaning
    • Device
    • Etch
    • Lithography
    • Materials
    • Packaging
  • Technology & Market Conferences – These conference sessions will provide the latest insights on market trends, sustainability, smart manufacturing, test, metrology and inspection, cybersecurity and compound power semiconductors.
    • Compound Power Semiconductor Summit – Thought leaders share their insights on emerging technology trends and market forecasts for SiC, GaN and Diamond WBG power semiconductors.
    • Cybersecurity Seminar – Subject matter experts discuss a comprehensive, standards-based cybersecurity frameworks to enhance supply chain security and accelerate actionable solutions.
    • Market Trends Forum – Leading research organizations and consulting firms provide insights into the semiconductor industry’s market dynamics.
    • Metrology and Inspection (MI) Forum – Technology leaders across the entire supply chain unveil cutting-edge technological shifts in metrology and inspection.
    • Smart Manufacturing Forum – Presenters explore the role of digital twin and multimodal technologies in enhancing manufacturing efficiency, as well as the sweeping changes that AI will bring to manufacturing environments.
    • Sustainability Forum – Experts share the latest developments and implications of PFAS regulations in the semiconductor industry.
    • Test Forum – Speakers present a comprehensive roadmap of the test technologies demanded by the AI era and advanced packaging innovations.
  • Enhanced Business Programs – The Investment Forum, designed to attract investments in Korean semiconductor companies, has more than doubled its previous size.
    • New: Netherlands Semiconductor R&D Collaboration Seminar – A platform to establish new partnerships between Dutch investment agencies, companies, and Korean enterprises.
    • New: Vietnam Investment Forum – A detailed overview of investment opportunities in Vietnam, an emerging hub for semiconductor manufacturing, fostering collaboration with Korean companies.
    • U.S. Investment Forum – A discussion of the latest updates on industry policies and the CHIPS Act with representatives from the U.S. Department of Commerce, and talent development initiatives with representatives from Arizona, Indiana, New York, Oregon, and Texas.
  • Supplier Search Program – This popular SEMICON Korea business-matching program will host nearly 100 meetings between global chipmakers such as GlobalFoundries, Kioxia, Micron as well as equipment, materials and parts suppliers to support domestic semiconductor companies’ expansion into overseas markets.

Workforce Development

The Meet the Expert! program returns to help address the talent shortage, with engineers sharing insights on career development for STEM students aspiring to enter the semiconductor industry.

The Women-in-Technology program will again focus on increasing diversity in the workforce. Female leaders in high-tech will offer guidance on career paths and present strategies for enhancing workplace diversity.

Online Registration

Online registration for SEMICON Korea 2025 is open from December 9, 2024 to February 12, 2025. Registration for the exhibition and keynote speeches is free during this period, while conference registration is available at discounted early bird rates.

For more information, please visit the SEMICON Korea 2025 website.

About SEMI

SEMI® is the global industry association connecting over 3,000 member companies and 1.5 million professionals worldwide across the semiconductor and electronics design and manufacturing supply chain. We accelerate member collaboration on solutions to top industry challenges through Advocacy, Workforce Development, Sustainability, Supply Chain Management and other programs. Our SEMICON® expositions and events, technology communities, standards and market intelligence help advance our members’ business growth and innovations in design, devices, equipment, materials, services and software, enabling smarter, faster, more secure electronics. Visit www.semi.org, contact a regional office, and connect with SEMI on LinkedIn and X to learn more.  

Association Contacts

Jaegwan Shim/SEMI Korea 
Phone: 82+10.3014.9807
Email: [email protected] 

Sherrie Gutierrez/SEMI Corporate
Phone: 1.831.889.3800
Email: [email protected]

SOPOT, Poland — December 11, 2024 — Leading industry experts, economists, policymakers, and technology leaders will gather at the SEMI Industry Strategy Symposium Europe (ISS Europe) 2025, March 12-14 in Sopot, Poland, to explore the transformative role of Artificial Intelligence in driving Europe’s semiconductor industry forward. This year’s symposium will focus on how AI is set to become a key catalyst in enhancing Europe’s global competitiveness, with projections estimated to have a $2 trillion impact across multiple sectors by 2030.

ISSThemed AI: Catalyst to Propel Europe’s Competitiveness, ISS Europe 2025 will delve into the economic, technological, market, and societal trends reshaping the semiconductor industry. Experts will examine how AI applications across the semiconductor supply chain can foster innovation, efficiency, and co-opetition (collaboration and competition), which will be essential for Europe’s future leadership in the global market.  
“These are pivotal times for semiconductor industry leaders to align strategies and capitalize on growth opportunities powered by AI,” said Laith Altimime, President of SEMI Europe. “Europe has a unique opportunity to drive global semiconductor growth by harnessing AI to strengthen innovation, enhance supply chain resilience, and bolster Europe’s leadership. At ISS Europe, executives and leaders will share insights on advancing R&D, accelerating AI-driven technologies, and positioning Europe at the forefront of the digital revolution.”

ISS Europe 2025 Highlights

Session 1: Europe’s Strategy in a Shifting Geopolitical Landscape
Industry leaders will analyze how Europe is addressing global market trends and navigating geopolitical challenges to maintain a leadership position and drive innovation.

Session 2: Technology Roadmap to Net Zero: Breakthroughs and Energy Strategies
Experts will discuss breakthrough technologies, energy strategies, and AI-driven innovations shaping the semiconductor industry’s journey toward Net Zero and achieving sustainability goals.

Session 3: Shaping Europe’s Future Workforce: Strategies for Growth
Thought leaders will share actionable strategies to cultivate the workforce of tomorrow, emphasizing collaboration between industries, academia, and governments to drive innovation and sustainable growth.

Session 4: AI for Smarter Sustainable Manufacturing
Speakers will explore how AI can transform semiconductor manufacturing with smarter, sustainable processes while addressing workforce readiness and revitalizing European manufacturing capabilities.

Session 5: Driving Innovation to the Next Generation from Materials to System Level
Experts will highlight next-generation advancements in materials, design, and AI that are driving semiconductor innovation and enabling future technological breakthroughs.

Business Networking

ISS Europe 2025 will feature several networking activities including a welcome reception at the Grand Hotel Sopot and an exclusive gala dinner at Sheraton Sopot Hotel, where attendees can connect with peers to explore new business and collaboration opportunities. 

Sponsors

For more details, please visit the Industry Strategy Symposium Europe (ISS Europe) 2025 website and connect with SEMI Europe on LinkedIn or X @SEMIEurope (#ISSEurope).

About SEMI 

SEMI® is the global industry association connecting over 3,000 member companies and 1.5 million professionals worldwide across the semiconductor and electronics design and manufacturing supply chain. We accelerate member collaboration on solutions to top industry challenges through Advocacy, Workforce Development, Sustainability, Supply Chain Management and other programs. Our SEMICON® expositions and events, technology communities, standards and market intelligence help advance our members’ business growth and innovations in design, devices, equipment, materials, services and software, enabling smarter, faster, more secure electronics. Visit www.semi.org, contact a regional office, and connect with SEMI on LinkedIn and X to learn more.  

Contact Information:

Maria Daniela Perez / SEMI Europe 
Phone: +49 160 2562977 
Email: [email protected]  

Sherrie Gutierrez / SEMI Corporate
Phone: +1 831 889 3800 
Email: [email protected]

TOKYO – December 10, 2024 – SEMICON Japan, the region’s premier microelectronics industry conference and exhibition, opens tomorrow at Tokyo Big Sight. With more than 1,000 exhibitors from 35 regions, the conference gathers leaders from across the microelectronics manufacturing supply chain from December 11-13. SEMICON Japan 2024 will spotlight smart semiconductor applications for automotive, Internet of Things (IoT), and more, emphasizing industry insights, trends, and innovations that are powering the next wave of digital transformation. Registration is open.

SEMICON Japan

Themed Strong Together, this year’s SEMICON Japan will feature two new events, including the Advanced Design Innovation Summit (ADIS) that will detail the future of semiconductor design and verification. Additionally, the inaugural SEMI Global Standards Summit will look at future advancements of semiconductor manufacturing and industry standardization strategies focusing on three important themes: Smart Manufacturing for Future Factories, Packaging Architectures & Materials, and Environmental Sustainability.

“Japan’s focus on worldwide semiconductor industry collaboration and its critical role in the broader supply chain solidify it as a key region for innovation,” said Jim Hamajima, President of SEMI Japan. “SEMICON Japan will expand opportunities to connect with leaders across the global industry to further accelerate the pace of technological developments in growing sectors such as AI, automotive, IoT, 5G, and more. As the world becomes increasingly digital, SEMICON Japan is bringing the industry together to drive the next wave of groundbreaking technology.”

Notable speakers at the SuperTHEATER, SEMICON Japan’s biggest stage, will include:

  • Akira Amari: Former Member of the House of Representatives Honorary Chairman, Diet Members Caucus for the Promotion of Semiconductor Strategy
  • Tetsuro Higashi: Chairperson of the Board, Rapidus Chairman, Leading-Edge Semiconductor Technology Center 
  • Jim Keller: CEO, Tenstorrent
  • Makiko Eda: Managing Executive Officer, Chief Sustainability, DE&I Officer, Sumitomo 
  • Dario Gil: Senior Vice President and Director of IBM Research, IBM
  • Ho-Young Son: Vice President of Advanced Package Development, SK hynix 
  • Terushi Shimizu: Representative Director, President and CEO, Sony Semiconductor Solutions

Concurrent Events with SEMICON Japan 

  • Advanced Packaging and Chiplet Summit (APCS): This summit will include an exhibition area for technologies that support 2.5D, 3D, redistribution layers, through silicon vias, chiplets, and more. APCS will also feature networking opportunities and conference sessions led by the world’s top industry players. 
  • FLEX Japan: This event will bring device and material suppliers together with vendors who provide the final products, with the goal of creating new business opportunities within the flexible device and printed electronics sectors.

Other SEMICON Japan Highlights

  • Workforce Development Programs*: SEMICON Japan’s workforce development programs will include Mirai College at SEMICON*, where 51 semiconductor-related companies will gather to help attendees learn about the industry. In addition, 70 universities* from across Japan will share their latest research and provide collaboration opportunities for those in academia*. 
  • Technology Pavilions: The many technology pavilions at SEMICON Japan include the Quantum Computing, Ministry of the Environment, Power Electronics, Clean Room, and SEMI Sustainability HUB pavilions. Each pavilion will feature targeted exhibitions related to their focus area. 
  • Interactive Attractions: To help encourage semiconductor industry interest among the younger generation, SEMICON Japan will feature Yoichi Ochiai’s Passion Lab, an initeractive discussion led by media artist, Yoichi Ochiai. In addition, SEMICON STADIUM will allow attendees to see, touch, and experience semiconductors through sports-playing AI robots, such as AI basketball robot “CUE6” (Toyota Motor Corporation), table tennis robot “Forpheus” (Omron), baseball swing analysis using Fujitsu Human Motion Analytics (Fujitsu), and the fastest robot to solve a puzzle cube “TOKUFASTbot” (Mitsubishi Electric).

*Website (Japanese language)

SEMICON Japan 2024 Sponsors 

For more details, please see the SEMICON Japan 2024 Agenda-at-a-Glance. 

About SEMI 

SEMI® is the global industry association connecting over 3,000 member companies and 1.5 million professionals worldwide across the semiconductor and electronics design and manufacturing supply chain. We accelerate member collaboration on solutions to top industry challenges through Advocacy, Workforce Development, Sustainability, Supply Chain Management and other programs. Our SEMICON® expositions and events, technology communities, standards and market intelligence help advance our members’ business growth and innovations in design, devices, equipment, materials, services and software, enabling smarter, faster, more secure electronics. Visit www.semi.org, contact a regional office, and connect with SEMI on LinkedIn and X to learn more.  

Contact Information:

Association Contacts

Shuichi Sato/SEMI Japan
Phone: 81.3.3222.5757
Email: [email protected]

Sherrie Gutierrez / SEMI Corporate 
Phone: +1 831 889 3800 
Email: [email protected] 

Front-end and Back-end Segments Projected to Support Consecutive Growth from 2024 through 2026

TOKYO — December 9, 2024 — Global sales of total semiconductor manufacturing equipment by original equipment manufacturers (OEMs) are forecast to set a new industry record, reaching $113 billion in 2024, growing 6.5% year-on-year, SEMI announced today in its Year-End Total Semiconductor Equipment Forecast – OEM Perspective at SEMICON Japan 2024. Semiconductor manufacturing equipment growth is expected to continue in the following years, reaching new records of $121 billion in 2025 and $139 billion in 2026, supported by both the front-end and back-end segments.

SEMI Logo

“Three consecutive years of projected growth in investments in semiconductor manufacturing reflect the vital role our industry plays in underpinning the global economy and advancing technology innovation,” said Ajit Manocha, SEMI president and CEO. “Since our July 2024 forecast, the outlook for 2024 semiconductor equipment sales has brightened, especially with stronger-than-expected investments from China and in AI-related sectors. Together with our forecast extension through 2026, it highlights the robust growth drivers across segments, applications, and regions.”

Semiconductor Equipment Sales by Segment

After registering a record $96 billion in sales last year, the wafer fab equipment (WFE) segment, which includes wafer processing, mask/reticle, and fab facilities equipment, is projected to grow 5.4% to $101 billion in 2024. This marks an increase from the previously forecast $98 billion in SEMI’s 2024 Mid-Year Equipment Forecast. The upward revision mainly reflects the ongoing strong equipment investments in DRAM and high-bandwidth memory (HBM) driven by artificial intelligence (AI) computing. Additionally, China’s investments continue to play a significant role in the WFE market expansion. Looking ahead, WFE segment sales are projected to expand 6.8% in 2025 and 14% in 2026, reaching $123 billion due to increased demand for advanced logic and memory applications.

Following two years of contraction, the back-end equipment segment in 2024 saw a strong recovery in particular in the second half of the year. Sales of semiconductor test equipment are projected to rise 13.8% to $7.1 billion in 2024, while assembly and packaging (A&P) equipment sales are projected to increase 22.6% to $4.9 billion. Furthermore, the back-end segment growth is expected to accelerate, with test equipment sales surging 14.7% in 2025 and 18.6% in 2026, respectively, while A&P sales are forecast to grow 16% in 2025 followed by 23.5% expansion in 2026. The back-end segments’ growth is supported by the increasing complexity of semiconductor devices for high-performance computing and the expected increase in demand in the mobile, automotive, and industrial end-markets. 

SEMI 2024 Year-end Total*Equipment Forecast by segment


Wafer Fab Equipment Sales by Application

The sales of WFE for foundry and logic applications are expected to remain flat year-on-year at $58.6 billion in 2024, supported by resilient spending in mature nodes. The segment is forecast to see 2.8% growth in 2025 and to increase 15% to $69.3 billion in 2026, driven by increasing demand for leading-edge technology, the introduction of new device architectures including the transition to gate-all-around (GAA), and increased capacity expansion purchases.

Memory-related capital expenditures are projected to see significant increases through 2026 supported by increasing demand for HBM for AI deployment and ongoing technology migration. NAND equipment sales are expected to remain relatively soft in 2024, growing 0.7% to $9.3 billion as supply and demand continues to normalize, setting the stage for a 47.8% expansion to $13.7 billion in 2025 and 9.7% growth to $15.1 billion in 2026. Meanwhile, DRAM equipment sales are projected to see robust growth of 35.3% to $18.8 billion in 2024, followed by 10.4% and 6.2% year-on-year growth in 2025 and 2026, respectively.

SEMI 2024 Year-end Wafer Fab Equipment Forecast by Application


Semiconductor Equipment Sales by Region

China, Taiwan and Korea are expected to remain the top three destinations for equipment spending through 2026. China is projected to maintain the top position over the forecast period as the region’s equipment purchases continue to remain resilient despite the anticipated slowdown. Equipment shipments to China are projected to reach a record $49 billion in 2024, solidifying its lead over other regions. While equipment spending for most regions is expected to fall in 2024 before rebounding in 2025, China is expected to see a contraction in 2025 following significant investments over the past three years. All regions tracked are expected to see increases in 2026.

The SEMI forecast is based on collective input from top equipment suppliers, the SEMI Worldwide Semiconductor Equipment Market Statistics (WWSEMS) data collection program and the industry-recognized SEMI World Fab Forecast database. 

About SEMI Market Data

The Equipment Market Data Subscription (EMDS) from SEMI provides comprehensive market data for the global semiconductor equipment market. A subscription includes three reports: 

  • Monthly SEMI North American Billings Report, an early perspective of equipment market trends
  • Monthly Worldwide Semiconductor Equipment Market Statistics (WWSEMS), a detailed report of semiconductor equipment billings for seven regions and more than 22 market segments
  • Bi-annual Total Semiconductor Equipment Forecast – OEM Perspective, an outlook for the semiconductor equipment market

For more information online, please visit SEMI Market Data. 

About SEMI

SEMI® is the global industry association connecting over 3,000 member companies and 1.5 million professionals worldwide across the semiconductor and electronics design and manufacturing supply chain. We accelerate member collaboration on solutions to top industry challenges through Advocacy, Workforce Development, Sustainability, Supply Chain Management and other programs. Our SEMICON® expositions and events, technology communities, standards and market intelligence help advance our members’ business growth and innovations in design, devices, equipment, materials, services and software, enabling smarter, faster, more secure electronics. Visit www.semi.org, contact a regional office, and connect with SEMI on LinkedIn and X to learn more.

Association Contact
Samer Bahou/SEMI
Phone: 1.408.943.7870
Email: [email protected] 

MILPITAS, Calif. – December 2, 2024 – Global semiconductor equipment billings increased 19% year-over-year to US$30.38 billion in the third quarter of 2024, while quarter-over-quarter billings registered 13% growth during the same period, SEMI announced today in its Worldwide Semiconductor Equipment Market Statistics (WWSEMS) Report. 

SEMI Logo“The global semiconductor equipment market recorded robust growth in the third quarter of 2024 driven by investments aimed at supporting proliferation of Artificial Intelligence as well as production of mature technologies,” said Ajit Manocha, SEMI President and CEO. “The growth in equipment investments was spread across multiple regions seeking to bolster their chipmaking ecosystems, with North America posting the largest year-over-year gain while China continues to lead in spending.”  

Semiconductor Equipment Billings by region


Compiled from data submitted by members of SEMI and the Semiconductor Equipment Association of Japan (SEAJ), the WWSEMS Report is a summary of the monthly billings figures for the global semiconductor equipment industry. 

Following are quarterly billings data in billions of U.S. dollars with quarter-over-quarter and year-over-year changes by region:

Semiconductor Equipment market revenue by region

The SEMI Equipment Market Data Subscription (EMDS) provides comprehensive market data for the global semiconductor equipment market. The subscription includes three reports:

  • Monthly SEMI Billings Report, a perspective on equipment market trends
  • Monthly Worldwide Semiconductor Equipment Market Statistics (WWSEMS), a detailed report of semiconductor equipment billings for seven regions and 24 market segments
  • SEMI Semiconductor Equipment Forecast, an outlook for the semiconductor equipment market

Download a sample of the EMDS report.

For more information about the report or to subscribe, please contact the SEMI Market Intelligence Team at [email protected]. More details are also available on the SEMI Market Data webpage.  

About SEMI

SEMI® is the global industry association connecting over 3,000 member companies and 1.5 million professionals worldwide across the semiconductor and electronics design and manufacturing supply chain. We accelerate member collaboration on solutions to top industry challenges through Advocacy, Workforce Development, Sustainability, Supply Chain Management and other programs. Our SEMICON® expositions and events, technology communities, standards and market intelligence help advance our members’ business growth and innovations in design, devices, equipment, materials, services and software, enabling smarter, faster, more secure electronics. Visit www.semi.org, contact a regional office, and connect with SEMI on LinkedIn and X to learn more.

Association Contact

Samer Bahou/SEMI
Phone: 1.408.943.7870
Email: [email protected] 

MILPITAS, Calif. – November 19, 2024 – The global semiconductor manufacturing industry in the third quarter of 2024 showed strong momentum with all key industry indicators performing positive quarter-on-quarter (QoQ) increases for the first time in two years, SEMI announced today in its Q3 2024 publication of the Semiconductor Manufacturing Monitor (SMM) Report, prepared in partnership with TechInsights. The growth is fueled by seasonal factors and strong demand from investments in AI data centers, however, the consumer, automotive, and industrial segments are experiencing a slower pace of recovery. The growth trend is expected to continue into the fourth quarter of 2024.


SEMI & Tech Insights


After declining in the first half of 2024, electronic sales rebounded in Q3 2024, growing 8% QoQ, with a projected QoQ increase of 20% in Q4 2024. IC sales also rose by 12% QoQ in Q3 2024 and are expected to grow another 10% in Q4 2024. Overall, IC sales are forecasted to increase over 20% in 2024, primarily driven by memory products due to price improvement across the board and strong demand for data center memory chips. 

Similar to the electronics sales, semiconductor capital expenditures (CapEx) decreased in the first half of 2024, but the trend is turning positive starting in Q3 2024. Memory-related CapEx is surging 34% QoQ and 67% year-on-year (YoY) in Q3 2024 reflecting improvement in the memory IC market compared to the same period of the last year. In Q4 2024, total CapEx is expected to jump 27% relative to Q3 2024 levels and 31% YoY, with memory-related CapEx leading this growth at 39% YoY.

The semiconductor capital equipment segment remains strong and is performing better than previously expected due to substantial investments from China and increased spending for high-bandwidth memory and advanced packaging. Wafer Fab Equipment (WFE) spending increased 15% YoY and 11% QoQ in Q3 2024. China’s investment continues to play a significant role in the WFE market. Additionally, both the Test and the Assembly and Packaging segments experienced impressive YoY increases of 40% and 31%, respectively, in Q3 2024, and this growth is anticipated to continue for the remainder of the year. 

In Q3 2024, installed wafer fab capacity reached 41.4 million wafers per quarter (in 300mm wafer equivalent) and is projected to rise by 1.6% in Q4 2024. Foundry and Logic-related capacity continues to show stronger increases, growing 2.0% in Q3 2024 and is projected to rise 2.2% in Q4 2024 driven by capacity expansion for both advanced and mature nodes. Memory capacity increased 0.6% in Q3 2024 and is forecasted to maintain the same pace of growth in Q4 2024. This growth is driven by strong demand for high bandwidth memory (HBM) but is partially offset by process node transitions.

“The semiconductor capital equipment segment continues to exhibit growth momentum, bolstered this year by strong investments from China and increased spending on advanced technologies,” said Clark Tseng, Senior Director of Market Intelligence at SEMI. “Additionally, the continued expansion of fab capacity, especially in the foundry and logic segments, underscores the industry’s commitment to meeting the growing demand for advanced semiconductor technologies.” 

“2024 has shown two sides within the semiconductor industry,” said Boris Metodiev, Director of Market Analysis at TechInsights. “While consumer, automotive, and industrial markets have struggled, AI has thrived, boosting average selling prices in memory and logic products. As interest rates decrease heading into 2025, consumer sentiment is expected to improve, encouraging larger purchases and supporting both the consumer and automotive markets.” 

IC salesCAPEX Versus Fab Capacity

Sources: SEMI (www.semi.org) and TechInsights (www.techinsights.com), November 2024

The Semiconductor Manufacturing Monitor (SMM) report provides end-to-end data on the worldwide semiconductor manufacturing industry. The report highlights key trends based on industry indicators including capital equipment, fab capacity, and semiconductor and electronics sales, and includes a capital equipment market forecast. The SMM report also contains two years of quarterly data and a one-quarter outlook for the semiconductor manufacturing supply chain including leading IDM, fabless, foundry, and OSAT companies. An SMM subscription includes quarterly reports. 

Download a sample of the Semiconductor Manufacturing Monitor report. 

For more information on the report or to subscribe, please contact the SEMI Market Intelligence Team at [email protected]. Details on SEMI market data are available at SEMI Market Data.  

About SEMI

SEMI® is the global industry association connecting over 3,000 member companies and 1.5 million professionals worldwide across the semiconductor and electronics design and manufacturing supply chain. We accelerate member collaboration on solutions to top industry challenges through Advocacy, Workforce Development, Sustainability, Supply Chain Management and other programs. Our SEMICON® expositions and events, technology communities, standards and market intelligence help advance our members’ business growth and innovations in design, devices, equipment, materials, services and software, enabling smarter, faster, more secure electronics. Visit www.semi.org, contact a regional office, and connect with SEMI on LinkedIn and X to learn more.

Association Contact 

Samer Bahou/SEMI Corporate
Phone: 1.408.943.7870
Email: [email protected]

MILPITAS, Calif. — November 12, 2024 — Worldwide silicon wafer shipments increased 5.9% quarter-over-quarter to 3,214 million square inches (MSI) in the third quarter of 2024 and registered 6.8% growth from the 3,010 million square inches recorded during the same quarter last year, the SEMI Silicon Manufacturers Group (SMG) reported in its quarterly analysis of the silicon wafer industry. 

SEMI“The third quarter wafer shipment results continued the upward trend which started in the second quarter of this year,” said Lee Chungwei (李崇偉), Chairman of SEMI SMG and Vice President and Chief Auditor at GlobalWafers. “Inventory levels have declined throughout the supply chain but generally remain high. Demand for advanced wafers used for AI continues to be strong. However, the silicon wafer demand for automotive and industrial uses continues to be muted, while the demand for silicon used for handset and other consumer products has seen some areas of improvement. As a result, 2025 is likely to continue upward trends, but total shipments are not yet expected to return to the peak levels of 2022.”

MSI

Data cited in this release include polished silicon wafers, including those used as virgin test wafers, as well as epitaxial silicon wafers, and non-polished silicon wafers shipped by the wafer manufacturers to end users.

Silicon wafers are the fundamental building material for the majority of semiconductors, which are vital components of all electronic devices. The highly engineered thin disks are produced in diameters of up to 300 mm and serve as the substrate material on which most semiconductors are fabricated.

The SMG is a sub-committee of the SEMI Electronic Materials Group (EMG) and is open to SEMI members involved in manufacturing polycrystalline silicon, monocrystalline silicon or silicon wafers (e.g., as cut, polished, epi). The SMG facilitates collective efforts on issues related to the silicon industry including the development of market information and statistics about the silicon industry and the semiconductor market.

For more information, visit SEMI Worldwide Silicon Wafer Shipment Statistics.

About SEMI

SEMI® is the global industry association connecting over 3,000 member companies and 1.5 million professionals worldwide across the semiconductor and electronics design and manufacturing supply chain. We accelerate member collaboration on solutions to top industry challenges through Advocacy, Workforce Development, Sustainability, Supply Chain Management and other programs. Our SEMICON® expositions and events, technology communities, standards and market intelligence help advance our members’ business growth and innovations in design, devices, equipment, materials, services and software, enabling smarter, faster, more secure electronics. Visit www.semi.org, contact a regional office, and connect with SEMI on LinkedIn and X to learn more.

Association Contact

Samer Bahou/SEMI Corporate
Phone: 1.408.943.7870
Email: [email protected]

MUNICH, Germany – November 12, 2024 – The MEMS & Imaging Sensors Summit 2024, hosted by SEMI Europe and the MEMS & Sensors Industry Group, will open November 14 at the International Conference Center Munich (ICM), Germany. Bringing together industry leaders and innovators, the summit will showcase how advancements in MEMS and imaging sensor technologies are paving the way for a more sustainable and connected future. Registration is open.

Mems&ImagingThemed Sensor Revolution for a Connected Future, the summit will highlight recent developments in MEMS and imaging sensors, market trends, as well as the latest innovations that drive advancements across sectors like automotive and healthcare.

“The SEMI MEMS & Imaging Sensors Summit brings together industry stakeholders to explore transformative advancements in MEMS and sensing technologies for a smarter, sustainable, and more connected world,” said Laith Altimime, President of SEMI Europe. “We look forward to welcoming global industry leaders as they share insights on groundbreaking innovations aimed at addressing today’s challenges and driving tomorrow’s industry growth.” 

Program Highlights:

  • Smart Sensors for a Sustainable Future: Explore how advanced sensor technologies are enabling transformative use cases in sectors like healthcare and environmental monitoring. 
  • 300mm MEMS Foundries – A Game Changer: Learn how 300mm-capable MEMS foundries are set to revolutionize MEMS manufacturing, providing scalability and efficiency for a variety of applications.
  • Imaging to Vision – AI and Machine Learning for Edge Applications: Discover a paradigm shift in imaging technologies with AI-powered solutions that dramatically reduce energy consumption and latency for edge applications. 
  • Emerging MEMS Trends: Dive into the latest MEMS architectures and materials for future growth opportunities in applications ranging from automotive to microfluidics to environmental monitoring​.
  • Next-Generation Imaging Technologies: Explore cutting-edge innovations in shortwave infrared (SWIR) imaging, multispectral cameras, and hyperspectral imaging that are enabling new capabilities in areas like healthcare, smart mobility, and industrial automation. 
  • Health and Wearables: Discover the latest sensor technologies for monitoring vital signs in wearable devices, as well as non-invasive spectrometry for biomarker analysis. 
  • Smart Mobility and LiDAR Technology: Gain insights into how LiDAR sensors and advanced vision systems are shaping the future of smart mobility and autonomous vehicles. 

Featured Speakers

Premier Sponsors 

Industry-Leading Exhibitors at MEMS & Imaging Sensors Summit

  • AGP Co., Ltd
  • ASE Group
  • CEA-Leti
  • Comet Yxlon
  • Eurofins | MASER
  • FormFactor
  • Fraunhofer Institute for Silicon Technology
  • Lam Research
  • Philips MEMS & Micro Devices
  • Polyteknik AS
  • Pyxalis
  • QP Technologies (formerly Quik-Pak)
  • Schott AG
  • scia Systems GmbH
  • Science Foundry
  • Shenzhen Angstrom Excellence Technology Co. Ltd
  • Siemens EDA
  • Silex Semiconductors
  • Spraying Systems Deutschland GmbH
  • Ushio Inc.
  • ViALUX Messtechnik + Bildverarbeitung GmbH

For more information, please visit the MEMS & Sensors Imaging Summit website.

Stay connected with SEMI Europe on LinkedIn or X @SEMIEurope: #SensorsSummit #MEMS #Imaging #SEMIEurope 

About SEMI 

SEMI® is the global industry association connecting over 3,000 member companies and 1.5 million professionals worldwide across the semiconductor and electronics design and manufacturing supply chain. We accelerate member collaboration on solutions to top industry challenges through Advocacy, Workforce Development, Sustainability, Supply Chain Management and other programs. Our SEMICON® expositions and events, technology communities, standards and market intelligence help advance our members’ business growth and innovations in design, devices, equipment, materials, services and software, enabling smarter, faster, more secure electronics. Visit www.semi.org, contact a regional office, and connect with SEMI on LinkedIn and X to learn more. 

Association Contacts 

Sitong He / SEMI Europe 
Phone: +49 151 5546 2638
Email: [email protected]  

Samer Bahou / SEMI Corporate 
Phone: +1 408 943 7870 
Email: [email protected]